
How to Master Your Mindset, Understand Taxes and Build Wealth Step by Step
By Vivek Singh | The Finance Mastery Hub
Introduction: The Missing Link Between Success and Wealth
For a long time, I believed that mastering my mindset was the key to becoming wealthy.
I thought that if I developed discipline, stayed positive, worked harder and improved my skills, financial success would eventually follow.
There is truth in that belief. Your mindset influences your habits, your decisions and how you respond to challenges.
But over time, I realised something important: earning money and building wealth are two different skills.
You can work hard, increase your income and achieve professional success, yet still struggle to save money. You can receive a salary hike and find that your expenses increase almost immediately. You can even invest regularly without fully understanding the taxes that affect your financial decisions.
That is when financial knowledge becomes essential.
Understanding income tax brackets, managing your cash flow, controlling lifestyle inflation and building a long-term investment plan can help you make better use of the money you earn.
The real solution is not to choose between mindset and money management. It is to develop both.
In this article, we will explore how to strengthen your financial mindset, understand India’s income tax slabs and follow a practical step-by-step system for building wealth.
1. Why a Wealthy Mindset Alone Is Not Enough
A positive mindset can help you take action, learn new skills, remain consistent and recover from setbacks.
However, positive thinking alone cannot replace financial planning.
Imagine two professionals who earn the same salary.
The first professional spends most of the monthly income, makes financial decisions without a plan and starts thinking about savings only when something remains at the end of the month.
The second professional tracks expenses, understands tax obligations, maintains emergency savings and invests according to specific financial goals.
Both professionals may have equally strong ambitions. But their financial habits can produce very different outcomes over time.
The difference is not necessarily how much they earn. It is how they manage what they earn.
To build wealth, you need three things:
- The right mindset: To stay disciplined and make thoughtful decisions.
- Financial knowledge: To understand income, taxes, savings, debt and investments.
- Consistent action: To turn knowledge into habits that support your long-term goals.
Your mindset helps you move forward. Your financial system helps you make that progress sustainable.
2. Understand How Income Tax Brackets Work in India
One of the most useful financial concepts is understanding how progressive income tax works.
Under a progressive tax system, different portions of your taxable income are taxed at different rates. Reaching a higher tax bracket does not mean that all your income suddenly becomes taxable at that higher rate.
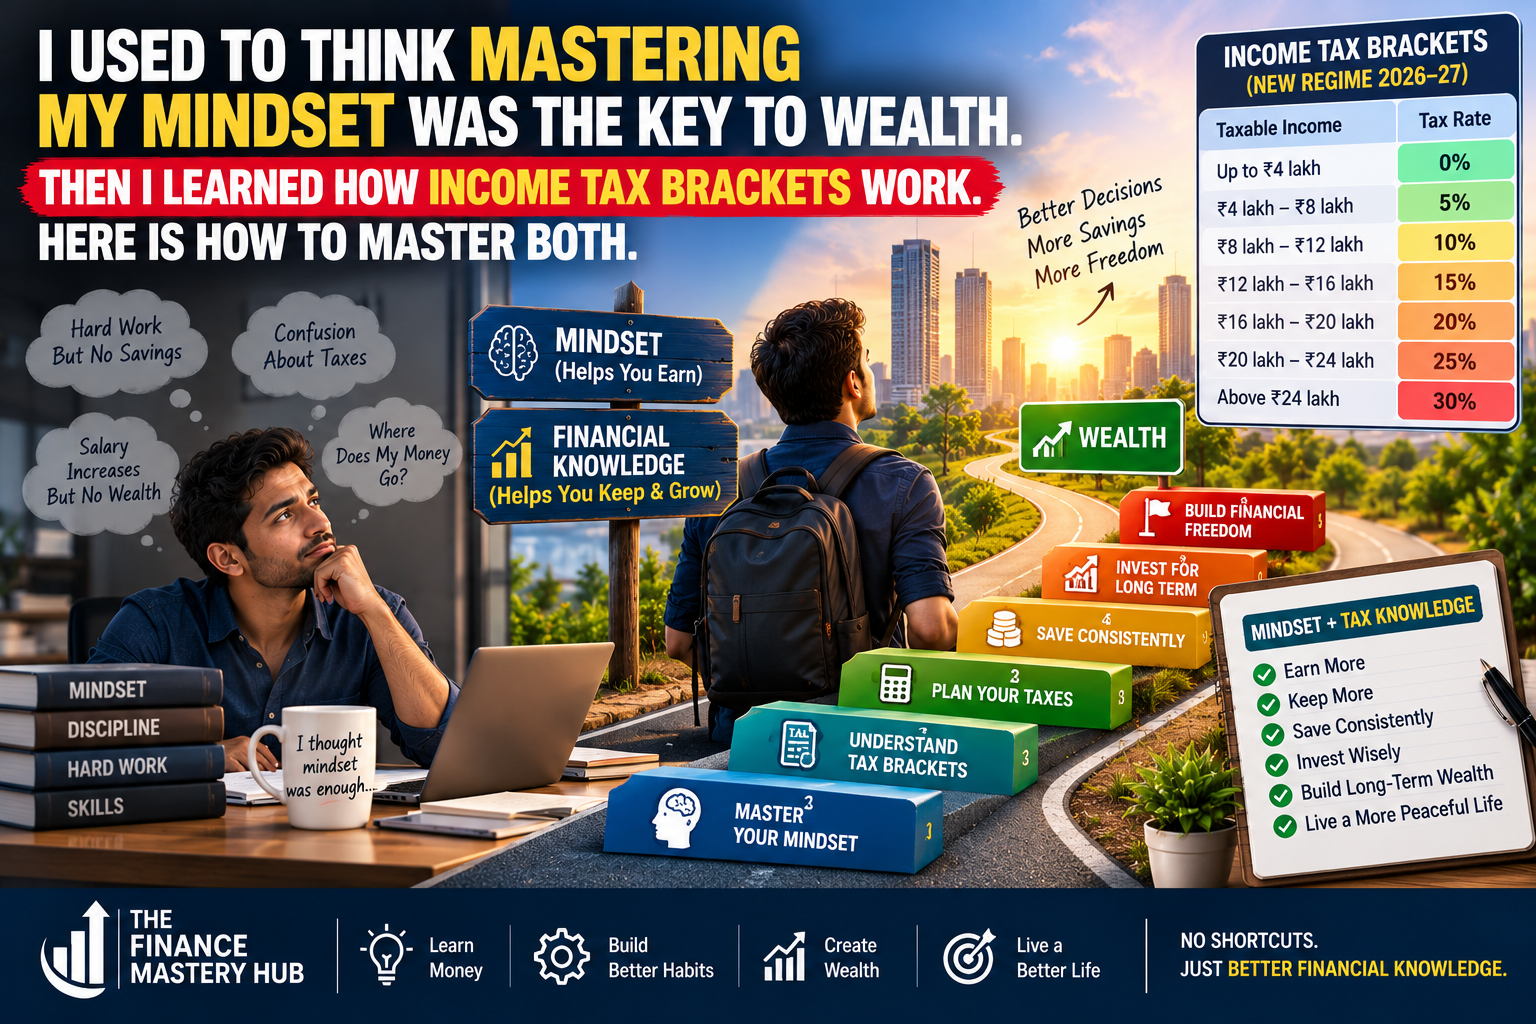
For the current tax year, 2026–27, the new tax regime provides the following general slab rates for individuals.
| Taxable income under the new regime | Tax rate |
|---|---|
| Up to ₹4 lakh | Nil |
| ₹4 lakh to ₹8 lakh | 5% |
| ₹8 lakh to ₹12 lakh | 10% |
| ₹12 lakh to ₹16 lakh | 15% |
| ₹16 lakh to ₹20 lakh | 20% |
| ₹20 lakh to ₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
These are general slab rates, not a complete tax calculation. Your final liability may depend on the type of income, applicable deductions, rebate eligibility, surcharge and health and education cess.
What does this mean in practice?
Suppose your taxable income is ₹15 lakh under the new tax regime.
For a simplified illustration, assuming all of this income is subject to the normal slab rates:
- The first ₹4 lakh is taxed at 0%: ₹0.
- The next ₹4 lakh is taxed at 5%: ₹20,000.
- The next ₹4 lakh is taxed at 10%: ₹40,000.
- The remaining ₹3 lakh is taxed at 15%: ₹45,000.
Total income tax before cess: ₹1,05,000.
Health and education cess at 4%: ₹4,200.
Illustrative total tax: ₹1,09,200.
This calculation assumes taxable income of ₹15 lakh, excludes special-rate income and does not account for any additional adjustments that may apply to an individual case.
Notice something important: the 15% rate applies only to the portion of taxable income in that slab. It does not apply to the entire ₹15 lakh.
That is the fundamental idea behind progressive taxation.
Why this knowledge matters
Without understanding tax brackets, you might make financial decisions based on incorrect assumptions.
You might believe that a salary increase will cause all your income to be taxed at a higher rate. Or you might reject an opportunity because you think the additional earnings will leave you worse off after tax.
In the ordinary case where the same progressive slab structure applies and there are no unusual interactions, moving into a higher bracket generally means that the additional income is taxed at a higher marginal rate—not that earning more automatically makes your entire income less valuable.
Understanding this distinction can help you evaluate salary increases, bonuses and career opportunities more confidently.
3. Learn the Difference Between Salary, Taxable Income and Take-Home Pay
Many people use the words salary, income and take-home pay as if they mean the same thing. They do not.
Annual salary or CTC: The compensation package offered by your employer. CTC can include employer contributions and benefits that do not arrive as cash in your bank account.
Taxable income: The amount used to calculate income tax after applying the relevant rules and permitted adjustments.
Income tax: The tax liability calculated under the applicable provisions.
Take-home pay: The amount actually credited to your bank account after relevant payroll deductions.
For example, an employee with a ₹15 lakh CTC does not necessarily have ₹15 lakh of taxable income or receive ₹15 lakh in cash during the year.
To understand your real financial position, review your salary structure, payslips, employer contributions, tax deductions and other applicable payroll items.
This simple exercise can prevent unrealistic budgeting and help you set achievable financial goals.
4. Step One: Master Your Mindset Before Managing Your Money
Financial improvement starts with awareness.
Before choosing investments or trying to reduce taxes, understand your current behaviour around money.
Ask yourself:
- Do I know where my salary goes every month?
- Do I spend more when my income increases?
- Do I make financial decisions because of social pressure?
- Do I avoid checking my bank balance because it makes me uncomfortable?
- Do I have a clear plan for saving and investing?
- Do I understand the financial risks I am taking?
Answer these questions honestly, without judging yourself.
The purpose is not to feel guilty about past mistakes. It is to identify the habits you can improve.
Your action plan
For the next 30 days, record your income and expenses. Categorise them into essentials, financial obligations, lifestyle spending and savings.
At the end of the month, identify one spending habit you want to change and one financial habit you want to strengthen.
You do not need to transform your entire financial life in a single day. Start with a change you can repeat consistently.
5. Step Two: Build a Tax-Planning Habit
Tax planning should not be a last-minute activity at the end of the financial year.
Understanding your tax position early can help you organise your documents, compare applicable tax regimes and avoid unnecessary confusion.
What should you do?
First, estimate your annual income.
Include salary, bonuses and other taxable income that may apply to you.
Second, understand the applicable tax regime.
India’s new tax regime is the default regime for eligible taxpayers, but the old regime may be available subject to the applicable rules. The better option depends on your income, deductions, exemptions and individual circumstances. <Cite refs={[“turn731305search1″,”turn731305search3”]}/>
Third, review eligible deductions and exemptions.
Do not assume that every deduction available under the old regime is also available under the new regime. Compare the rules carefully.
Fourth, check tax deducted at source.
Review the tax deducted by your employer and compare it with your estimated annual liability.
Fifth, keep your documents organised.
Maintain salary slips, Form 16, relevant investment documents, bank interest details and other records needed for your tax return.
Remember that tax planning means making informed decisions within the law. Buying a financial product solely to save tax may not be sensible if it does not support your actual financial goals.
6. Step Three: Pay Yourself Before Lifestyle Spending
A common financial mistake is to save whatever remains after all expenses have been paid.
The problem is that there may be very little left.
A more reliable approach is to decide how much you can save or invest and set that money aside soon after receiving your salary, while ensuring that essential expenses and required payments are covered.
A practical example
Imagine your monthly take-home salary is ₹80,000.
You could start with an illustrative budget like this:
| Category | Monthly amount |
|---|---|
| Essential expenses | ₹35,000 |
| Loan and other obligations | ₹10,000 |
| Savings and investments | ₹15,000 |
| Lifestyle and personal spending | ₹15,000 |
| Buffer for irregular expenses | ₹5,000 |
| Total | ₹80,000 |
This is only an example. Your own allocation should reflect your actual expenses, debts, family responsibilities and goals.
If you have expensive debt or no emergency savings, your priorities may differ. You might need to build a starter emergency fund while developing a repayment plan for high-interest debt.
The important point is to give your income a purpose before the month begins.
The salary-increase rule
Whenever your income increases, consider directing a portion of the additional take-home pay toward savings, debt repayment or long-term goals before increasing your lifestyle expenses.
You can still enjoy the rewards of your hard work. The goal is to prevent every salary increase from disappearing into new spending commitments.
7. Step Four: Build an Emergency Fund Before Taking Unnecessary Risks
Investing is important, but financial security also requires preparation for unexpected events.
A job loss, medical expense, urgent family responsibility or major repair can disrupt even a well-planned budget.
An emergency fund provides accessible money for such situations, reducing the need to borrow or sell long-term investments at an unfavourable time.
How to build one
- Calculate your essential monthly expenses.
- Set an initial target based on your circumstances.
- Work toward three to six months of essential expenses as a practical starting point.
- Keep the money in accessible, relatively low-risk options.
- Replenish the fund after using it for a genuine emergency.
For example, if your essential monthly expenses are ₹40,000, a three-to-six-month target would be ₹1.2 lakh to ₹2.4 lakh.
You do not need to save this amount immediately. Build it gradually through consistent contributions.
If your income is irregular or you have significant dependants, you may need a larger buffer.
8. Step Five: Invest According to Your Goals, Not Your Emotions
Once your financial foundation is reasonably stable, begin planning how to invest for future goals.
Do not invest simply because a friend has earned a high return or a social media post promises quick wealth.
Instead, identify what you are investing for.
- Short-term goals may require stability and easy access to money.
- Medium-term goals may call for a balance between risk and liquidity.
- Long-term goals may allow you to consider diversified growth investments, depending on your circumstances and risk tolerance.
Before investing, understand the potential loss, fees, liquidity restrictions, tax treatment and time horizon.
Diversification can reduce concentration risk, but it cannot eliminate all investment risk.
Review your plan periodically instead of reacting to every market movement.
The objective is not to make every investment successful. It is to build a financial strategy that you understand and can follow through different market conditions.
9. Step Six: Track Your Net Worth, Not Just Your Salary
Your salary tells you how much you earn. Your net worth gives you a broader view of your financial position.
A simple formula is:
Net worth = Total assets − Total liabilities
Assets may include savings, investments and other assets you own. Liabilities may include outstanding loans and other financial obligations.
Review your net worth periodically, perhaps every three or six months.
Ask yourself:
- Are my savings increasing?
- Is my expensive debt decreasing?
- Am I investing consistently?
- Am I becoming more financially prepared for unexpected expenses?
- Am I making progress toward my goals?
A high salary can support wealth creation, but it does not guarantee it. Your financial position depends on how income, spending, assets and liabilities evolve over time.
10. Your 30-Day Plan to Master Mindset and Money
Here is a simple plan you can start today.
Days 1–7: Understand your current position
- Record all income and expenses.
- Review bank statements and outstanding loans.
- Calculate your current savings.
- Identify the habits that make managing money difficult.
Days 8–14: Understand your taxes
- Estimate your annual taxable income.
- Review the current income tax slabs.
- Compare the applicable old and new regimes if eligible.
- Check your tax deductions and organise the necessary documents.
Days 15–21: Build your financial system
- Create a monthly budget.
- Set a realistic savings target.
- Start or strengthen your emergency fund.
- Establish a repayment plan for expensive debt.
Days 22–30: Prepare for long-term growth
- Define your short-, medium- and long-term financial goals.
- Review existing investments.
- Identify an investment approach that matches your risk tolerance.
- Schedule a monthly financial review.
At the end of 30 days, you may not have achieved every financial goal. That is perfectly fine.
You will, however, have a clearer understanding of your financial position and a system for making better decisions.
Conclusion: Mindset Helps You Earn. Knowledge Helps You Build.
I once thought that mastering my mindset was the key to wealth.
I now see that mindset is only one part of the process.
You also need to understand how your income is taxed, how much you actually take home, where your money goes and how to prepare for the future.
The most useful financial habits are often simple:
- Understand your tax position instead of making assumptions.
- Budget according to your actual take-home income.
- Save consistently and control lifestyle inflation.
- Build an emergency fund.
- Invest according to your goals and risk tolerance.
- Review your financial progress regularly.
You do not need to become a tax expert or a professional investor to improve your financial life. You need to understand the basics, ask questions when necessary and make informed decisions consistently.
Remember: your income creates opportunities, your habits influence your decisions, and your financial knowledge helps you use your money wisely.
At The Finance Mastery Hub, we believe that financial education is not about shortcuts or overnight success. It is about learning, making better decisions and building a stronger financial future—one step at a time.
Disclaimer
This article is for educational and informational purposes only and does not constitute personalised tax, legal or investment advice. Tax rules can change, and the treatment of income depends on individual circumstances. Verify the applicable provisions with the Income Tax Department or consult a qualified tax professional before making tax-related decisions.