
By Vivek Singh | The Finance Mastery Hub
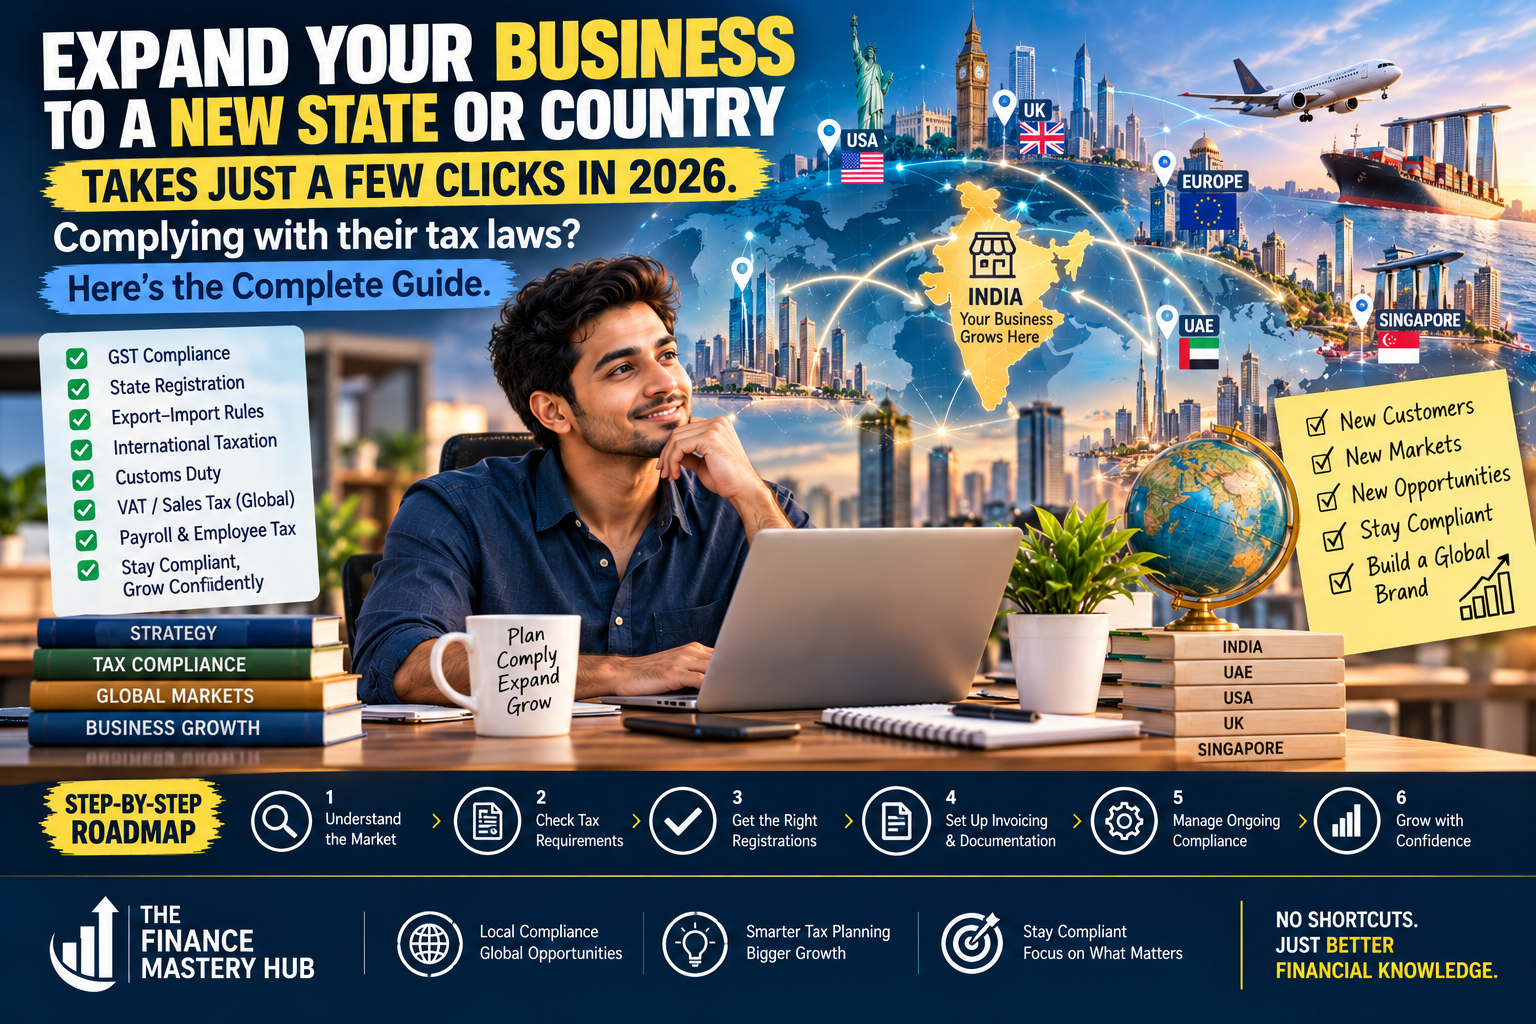
Introduction: Expanding your business is easier than ever—but are your taxes ready?
Imagine that you run a small clothing business in Jaipur.
For the first few years, you sell products to customers in Rajasthan. Your business grows, your website attracts more visitors, and customers from Maharashtra, Karnataka and Delhi start placing orders.
You then decide to sell through an international marketplace. Within a few weeks, customers from the UAE, the UK and the United States are buying your products.
It sounds like a success story—and it is.
But there is another side to this growth.
Are you required to register for GST in another Indian state? What happens if your products are stored in a warehouse outside Rajasthan? Do you need an Importer Exporter Code (IEC)? Will you have to pay customs duties? Could your overseas operations create a tax presence in another country?
These questions matter because business expansion is not only about finding customers. It is also about understanding the tax responsibilities that come with serving them.
In 2026, many business processes are becoming more digital and streamlined. However, digital registration and online selling do not remove the need to follow local tax laws.
This guide explains how Indian businesses can expand across states and international markets while managing their tax responsibilities.
1. Why business expansion creates new tax responsibilities
When a business enters a new market, its tax position may change depending on how it operates.
For example, there is a difference between:
- Selling products from your existing warehouse to a customer in another state.
- Storing products in a warehouse located in another state.
- Opening a branch office in another state.
- Hiring employees or sales representatives in another country.
- Providing digital services to customers overseas.
- Establishing a subsidiary or separate legal entity abroad.
Each arrangement can create different tax and reporting requirements.
Before expanding, understand these five areas:
- Indirect taxes such as GST, VAT or sales tax.
- Corporate income tax and international taxation.
- Customs duties and import-export regulations.
- Payroll taxes and withholding obligations.
- Transfer pricing and cross-border financial transactions.
The exact rules depend on the country, state, business structure, product and nature of the transaction.
2. Expanding your business to another Indian state: What happens under GST?
India follows a destination-based GST system. However, interstate and intrastate transactions are treated differently.
Intrastate supply
When the location of the supplier and the place of supply are in the same state, a transaction is generally treated as an intrastate supply.
For example:
A business registered in Uttar Pradesh sells products to a customer in Uttar Pradesh.
Depending on the transaction, CGST and SGST generally apply.
Interstate supply
When the location of the supplier and the place of supply are in different states, the transaction is generally treated as an interstate supply.
For example:
A business registered in Uttar Pradesh sells goods to a customer in Maharashtra.
IGST generally applies.
Important: The place-of-supply rules determine the tax treatment. The customer’s address alone does not decide every GST question, particularly for services and certain special transactions.
Do you need GST registration in every state?
Not automatically just because you have customers in different states.
However, GST registration may be required in another state when your business establishes a taxable place of business there or makes taxable outward supplies from that state, subject to the applicable provisions and exceptions.
For example:
- Your head office is in Uttar Pradesh.
- You open a branch office in Maharashtra.
- The Maharashtra branch starts making taxable supplies.
You may need a separate Maharashtra GST registration.
A business with multiple state registrations under the same PAN generally has separate GSTINs for those states. Registrations in different states are treated as distinct persons under GST law, and certain transactions between them can be taxable even when no money is charged.
Solution: Before opening a branch, warehouse or other business location, get a state-wise GST assessment. Do not assume that your existing GSTIN automatically covers every new state.
3. The important GST developments in 2026
The GST Council has recommended process improvements that may make business expansion easier.
One important recommendation from its 57th meeting, held on 8 October 2026, concerns small sellers supplying goods through e-commerce platforms.
Simplified registration for certain small e-commerce sellers
The Council recommended introducing Rule 14B for eligible small suppliers selling goods through e-commerce operators in states where they do not have a physical presence.
The proposed mechanism allows eligible sellers, subject to specified conditions, to declare an e-commerce operator’s warehouse in that state as their principal place of business and obtain registration through an automatic system-based process.
One of the stated conditions concerns passing on input tax credit of no more than ₹2.5 lakh per month, with specified exclusions.
This is intended to help small businesses expand through e-commerce platforms without necessarily establishing a conventional physical business location in every state.
Do not misunderstand this development: It is a conditional registration mechanism, not a general exemption from state GST registration for every seller. Check the applicable notification, rules and portal functionality before relying on it.
Faster GST registration amendments
An official government FAQ published on 9 October 2026 also explains changes to registration amendments.
For example, adding an additional place of business is now subject to automatic system processing under the described amendment mechanism.
However, the treatment of a change in the principal place of business differs. For normal taxpayers, that amendment continues to require officer approval; the simplified Rule 14A route has different treatment.
Practical lesson: Digital processes can reduce administrative delays, but businesses must still provide accurate information and the required documents.
4. Expanding internationally: Understand the tax rules before accepting overseas orders
Selling to a customer in another country does not automatically mean your business has to establish a company there.
However, it may create tax obligations depending on the nature of your activities.
Consider this example:
An Indian digital marketing agency provides services to a client based in the United Kingdom.
The agency receives payment in foreign currency and performs the work from India.
The transaction may qualify as an export of services under Indian GST law if all statutory conditions are satisfied.
But if the agency opens an office in the UK, employs staff there or creates a taxable business presence, additional UK tax obligations may arise.
International expansion requires you to examine several areas.
A. GST and export of services from India
Export of services is treated as a zero-rated supply under the IGST Act, subject to the applicable legal conditions.
Broadly, the statutory requirements include:
- The supplier of the service is located in India.
- The recipient is located outside India.
- The place of supply is outside India.
- Payment is received in convertible foreign exchange or in Indian rupees where permitted by the Reserve Bank of India.
- The supplier and recipient are not merely establishments of the same person, subject to any applicable legislative changes.
A foreign customer alone does not automatically make a transaction an export of services.
What is LUT?
A registered exporter may furnish a Letter of Undertaking (LUT) in Form GST RFD-11, subject to eligibility and prescribed conditions.
An eligible business can use an LUT to export qualifying goods or services without paying IGST upfront and claim a refund of eligible unutilised input tax credit, subject to the law.
Practical solution:
- Confirm that your service qualifies as an export.
- Review the place-of-supply rules.
- Obtain GST registration if required.
- Furnish an LUT where eligible.
- Issue invoices with the appropriate export details.
- Maintain client agreements and payment records.
- Reconcile export invoices with bank receipts and GST returns.
- Review refund eligibility and supporting documents.
B. VAT, GST or sales tax in the destination country
Different countries have different indirect tax systems.
For example:
- The United Kingdom operates VAT.
- The European Union operates VAT systems across member states.
- Australia operates GST.
- The United States has state and local sales tax systems.
A business selling products or digital services internationally may have to register and collect local indirect tax depending on the destination country’s rules, turnover thresholds, customer type, product category and business presence.
For example, an Indian company selling digital subscriptions to overseas consumers may face different obligations from a company providing services to a registered business customer.
Solution: Before entering a new country, check its VAT, GST or sales tax rules. Do not assume that Indian GST compliance is sufficient for every international transaction.
5. Permanent Establishment: Can your business become taxable in another country?
This is one of the most important concepts in international taxation.
A Permanent Establishment (PE) generally refers to a sufficient business presence in another country that may allow that country to tax profits attributable to that presence under its domestic law and applicable tax treaty.
The exact definition depends on the relevant country’s law and the applicable Double Taxation Avoidance Agreement (DTAA).
A business may need to examine PE risk when it:
- Opens an office or branch overseas.
- Maintains certain business premises abroad.
- Uses employees or representatives to conduct business activities.
- Has an agent who habitually concludes contracts on its behalf.
- Carries out activities that cross the relevant treaty’s PE threshold.
Example
An Indian consulting company starts serving customers in Singapore.
Initially, its employees work from India and provide remote services.
Later, the company sends employees to Singapore for extended periods and opens a local office.
The company’s tax position may change because its overseas activities could create a taxable presence.
This does not mean every overseas employee or customer automatically creates a PE. The facts, domestic law and relevant treaty must be examined.
Solution: Before establishing overseas offices, hiring local teams or authorising representatives to negotiate and conclude contracts, obtain a country-specific PE review.
6. Customs duty and import-export compliance
If your business deals with physical goods, customs compliance becomes an important part of expansion.
Suppose your Indian company manufactures electronic accessories and wants to sell them to customers in Germany.
You need to understand:
- Export documentation.
- Product classification and applicable HS codes.
- Customs declarations.
- Shipping and insurance.
- Product-specific licences and restrictions.
- Destination-country import duties.
- Product standards and labelling requirements.
What is IEC?
IEC stands for Importer Exporter Code.
It is issued by the Directorate General of Foreign Trade (DGFT) and is generally required for importing or exporting goods from India, unless a specific exemption applies.
IEC is based on the entity’s PAN.
For goods, the commonly required documents include:
- Commercial invoice and packing list.
- Shipping bill or bill of export.
- Bill of lading or airway bill, depending on the transport method.
- Any additional product-specific certificate, licence or approval required by law.
Service exporters should note that IEC is generally not required merely to export services, except in relevant cases such as when benefits under the Foreign Trade Policy are claimed.
Solution: Before shipping products, obtain the necessary IEC where required, confirm product restrictions, classify the goods correctly and coordinate customs documentation with your logistics provider.
7. Income tax, withholding tax and double taxation
International business transactions can create income tax responsibilities in more than one country.
For example, an Indian company may receive income from a foreign client. The foreign country may impose withholding tax depending on the nature of the payment and its domestic law.
India may also tax the company’s income under applicable Indian tax rules.
This raises an important question:
Can the same income be taxed twice?
India has Double Taxation Avoidance Agreements with several countries. Depending on the treaty, the taxpayer’s circumstances and applicable domestic law, relief may be available through a foreign tax credit or another treaty mechanism.
What should a business do?
- Identify the country from which income is received.
- Understand whether the payment is subject to withholding tax.
- Review the applicable DTAA.
- Obtain a Tax Residency Certificate where required.
- Collect relevant withholding tax certificates.
- Maintain supporting invoices and bank records.
- Review eligibility for foreign tax credit in India.
- File applicable tax forms and disclosures.
Do not assume that every payment from a foreign customer is tax-free in that country or that a DTAA automatically removes all withholding tax.
8. Transfer pricing: Important when your business operates through related companies
Suppose an Indian company establishes a subsidiary in the UAE.
The Indian company provides management services, technology support and marketing assistance to the UAE subsidiary.
How much should the UAE company pay the Indian company?
The price cannot simply be selected without considering applicable transfer pricing rules.
International transactions between associated enterprises may need to follow the arm’s length principle.
This means that the price should broadly reflect what independent parties would agree under comparable circumstances.
Common related-party transactions include:
- Management fees.
- Technical services.
- Software and technology charges.
- Royalty payments.
- Loans and interest.
- Purchase and sale of goods.
- Shared employee or administrative costs.
Solution: Maintain intercompany agreements, identify related-party transactions, document the pricing methodology and assess applicable transfer pricing reporting requirements in each country.
9. Payroll and employee tax compliance
Business expansion often involves hiring people in new locations.
This creates another set of responsibilities.
For example, if an Indian business hires employees in another country, it may need to consider:
- Local payroll registration.
- Income tax withholding.
- Social security contributions.
- Employment taxes.
- Local labour laws.
- Employee benefits and insurance.
- Permanent establishment implications.
Even remote working arrangements can require careful review depending on where the employee works and what activities they perform.
Solution: Before hiring employees in a new country, review the local payroll and employment tax requirements. Do not treat overseas payroll as a simple extension of your Indian salary process.
10. A practical example: How an Indian business can expand safely
Let’s understand this through a fictional business.
Business name: Sunrise Home Decor
Head office: Uttar Pradesh
Business activity: Manufacturing and selling home decoration products
Expansion plan: Maharashtra, UAE and the UK
The owner wants to expand without creating unnecessary tax risks.
Here is a practical approach.
| Expansion activity | Important compliance areas |
|---|---|
| Selling to Maharashtra customers | Interstate GST and place-of-supply rules |
| Opening a Maharashtra branch | Separate state GST registration assessment |
| Using an outside-state e-commerce warehouse | GST registration and eligibility for any applicable simplified scheme |
| Exporting products to the UAE | IEC, customs, export documents and UAE import rules |
| Selling products in the UK | UK VAT, customs and product regulations |
| Hiring overseas employees | Local payroll, employment taxes and PE review |
| Opening a foreign subsidiary | Local corporate tax, transfer pricing and Indian reporting |
The owner should not begin by registering everywhere without understanding the business model.
Instead, the owner should first identify the type of presence required in each market and then prepare a compliance plan.
11. The complete solution: A 10-step tax compliance plan for business expansion
Here is a practical system that businesses can follow before entering a new state or country.
Step 1: Identify your expansion model
Decide whether you will:
- Sell directly from India.
- Open a branch office.
- Establish a warehouse.
- Use an e-commerce marketplace.
- Appoint a distributor or agent.
- Hire local employees.
- Establish a foreign subsidiary.
The tax consequences can differ significantly between these models.
Step 2: Prepare a country-wise and state-wise tax map
Create a list of every market where you plan to operate.
For each market, identify:
- GST, VAT or sales tax.
- Registration requirements.
- Corporate income tax.
- Withholding tax.
- Payroll tax.
- Customs duty.
- Local reporting requirements.
Step 3: Review GST registration requirements
For Indian expansion, examine the location of the supplier, place of supply, business premises, warehouse arrangements and applicable registration provisions.
For international expansion, review the export treatment and the destination country’s indirect tax rules.
Step 4: Complete required registrations
Obtain the registrations and licences applicable to your model.
These may include:
- GST registration.
- IEC for goods imports and exports, where required.
- Local VAT or GST registration.
- Corporate registrations.
- Customs or product-specific approvals.
- Payroll registrations.
Step 5: Set up compliant invoicing
Your invoice should contain the information required by the applicable law.
Depending on the transaction, this may include:
- Legal business name and address.
- GSTIN or local tax identification number.
- Invoice number and date.
- Customer details.
- HSN or SAC classification, where applicable.
- Taxable value and tax rate.
- Place-of-supply information.
- Export-related declarations, where relevant.
Step 6: Build a documentation system
Maintain a central digital repository for:
- Customer contracts.
- Supplier agreements.
- Purchase orders.
- Sales invoices.
- Shipping documents.
- Bank statements.
- Foreign exchange records.
- Tax registrations.
- Return filings.
- Transfer pricing documents.
- Tax payment evidence.
Good documentation makes audits, reconciliations and refund claims easier to manage.
Step 7: Establish a monthly reconciliation process
Your finance team should reconcile:
- Sales ledger with tax returns.
- Purchase ledger with eligible input tax credit.
- Export invoices with shipping or service records.
- Foreign receipts with bank statements.
- Tax payable with payments made.
- Payroll records with tax deductions.
- Intercompany balances with supporting agreements.
Step 8: Review international tax exposure
If you have overseas employees, agents, offices, subsidiaries or warehouses, conduct a review of:
- Permanent Establishment risk.
- DTAA applicability.
- Withholding tax.
- Transfer pricing.
- Foreign tax credit.
- Local corporate tax.
Step 9: Create a compliance calendar
Do not depend on memory.
Create a calendar for each jurisdiction covering:
- Tax return due dates.
- Tax payment dates.
- Registration renewals.
- Annual filings.
- Payroll reporting.
- Customs documentation.
- Audit and transfer pricing deadlines.
The dates will vary by country, tax type and business structure.
Step 10: Review compliance before entering every new market
Before launching in a new state or country, get the proposed arrangement reviewed by a qualified tax professional familiar with that jurisdiction.
A small review before expansion can prevent expensive corrections later.
12. Common mistakes businesses should avoid
Many businesses focus on sales growth but ignore the tax structure behind it.
Avoid these mistakes:
- Assuming one GST registration automatically covers every Indian state.
- Treating every international sale as an export that is automatically zero-rated.
- Using an overseas warehouse without reviewing local registration requirements.
- Ignoring VAT or sales tax obligations in the destination country.
- Assuming that a foreign customer automatically creates—or never creates—a permanent establishment.
- Ignoring withholding tax on international payments.
- Setting related-party prices without transfer pricing documentation.
- Shipping goods without checking customs and product-specific requirements.
- Failing to reconcile foreign currency receipts and export invoices.
- Missing tax filing deadlines in different jurisdictions.
13. A 30-day action plan before expanding your business
You do not need to solve everything in one day. Start with a structured plan.
| Timeline | Action |
|---|---|
| Days 1–5 | Identify target markets and expansion model |
| Days 6–10 | Review GST, VAT and registration requirements |
| Days 11–15 | Review customs, export and import requirements |
| Days 16–20 | Assess income tax, PE and withholding tax exposure |
| Days 21–25 | Prepare invoicing, accounting and documentation systems |
| Days 26–30 | Finalise the compliance calendar and professional review |
At the end of 30 days, you should have a clear picture of the registrations, taxes, documents and reporting obligations associated with your expansion plan.
Conclusion: Grow your business, but build compliance into your growth strategy
In 2026, businesses have more opportunities than ever to reach customers across states and international markets.
A small business can sell through digital platforms, work with overseas clients, export products and build a global customer base.
But growth without tax planning can create unexpected liabilities, penalties, blocked input tax credit, delayed refunds and operational problems.
The solution is not to avoid expansion. It is to prepare for it.
Understand the tax rules before entering a new market. Maintain accurate records. Use technology to automate routine compliance. Review your tax position regularly and take professional advice when the rules become complex.
Remember:
Your business may expand with a few clicks, but sustainable growth requires the right tax knowledge.
No shortcuts. Just better financial knowledge.
Frequently Asked Questions (FAQs)
1. Can an Indian business sell products in every state using one GST number?
Not necessarily. A single GST registration does not automatically cover every state where a business has a taxable place of business or makes taxable outward supplies from that state. The applicable registration rules and exceptions must be examined.
2. Do I need IEC to provide services to foreign clients?
IEC is generally not required merely to export services, except in relevant cases such as when a service exporter seeks benefits under the Foreign Trade Policy. Check the current DGFT requirements for your activity.
3. Are exports from India exempt from GST?
Exports are treated as zero-rated supplies under the IGST Act, subject to the statutory conditions. Zero-rated treatment is different from an ordinary exempt supply. Eligible registered exporters may use an LUT route or another permitted mechanism.
4. Does selling to a foreign customer create a Permanent Establishment?
No, not automatically. PE depends on the nature of the business presence, activities, domestic law and the applicable tax treaty.
5. What is the biggest tax risk when expanding internationally?
There is no single risk for every business. Common areas include local indirect tax registration, permanent establishment, withholding tax, customs, payroll and transfer pricing.
6. Can technology automate all tax compliance?
Technology can help with invoicing, reconciliation, reporting, reminders and record management. However, it cannot replace legal interpretation, accurate classification or professional review of complex cross-border transactions.
Official resources and references
Use these government resources to verify the latest requirements before acting:
- CBIC – GST Acts and rules: https://taxinformation.cbic.gov.in/
- GST Portal – Registration and taxpayer services: https://www.gst.gov.in/
- GST Council – Recommendations and updates: https://gstcouncil.gov.in/
- DGFT – Import Export Code and Foreign Trade Policy: https://www.dgft.gov.in/
- Income Tax Department – International taxation and DTAA: https://www.incometax.gov.in/
- Income Tax Department – Transfer pricing: https://www.incometaxindia.gov.in/en/transfer-pricing
Disclaimer: This article is for general educational purposes and is based on the Indian regulatory context as understood in October 2026. Tax rules differ by jurisdiction, business structure, transaction and industry. GST Council recommendations are not automatically effective law; verify the relevant notifications, rules and commencement dates. International tax treatment must be checked under the domestic law and applicable tax treaty of each country. Consult a qualified tax professional before making registration, invoicing or cross-border structuring decisions.