
By Vivek Singh | The Finance Mastery Hub
Introduction: A High Salary Doesn’t Always Mean Financial Freedom
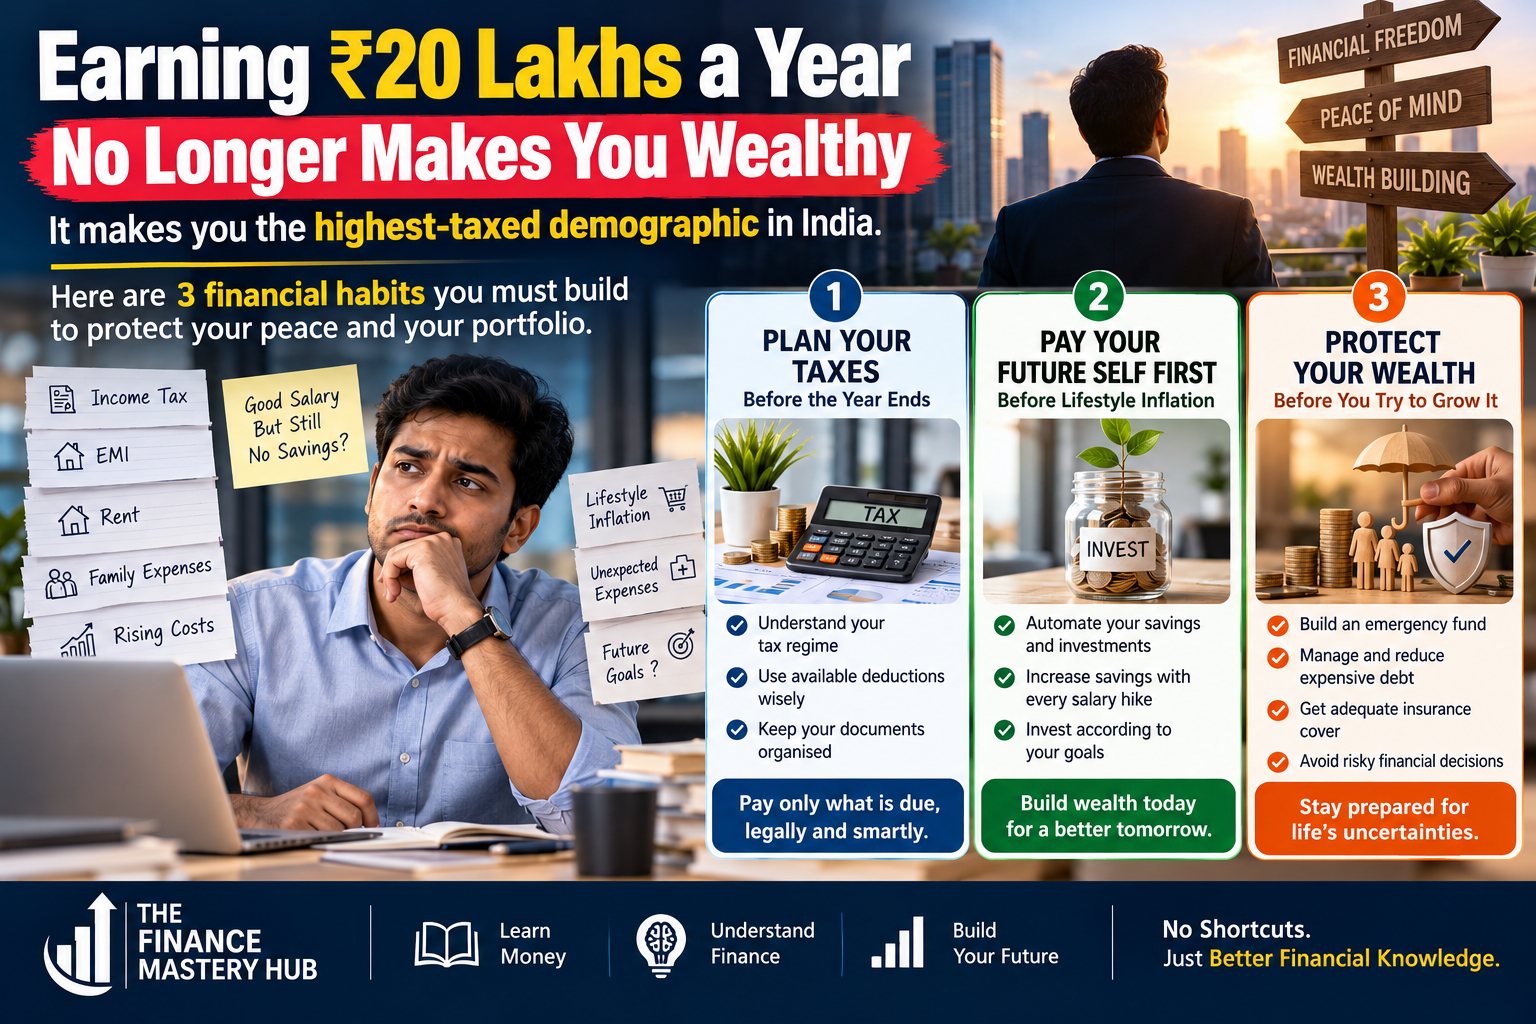
Imagine earning ₹20 lakh a year. From the outside, it may look like you have achieved financial success. You have a good job, a comfortable lifestyle and the ability to afford things that were once out of reach.
But behind the scenes, the reality can be very different.
Income tax reduces your take-home pay. Rent or home-loan EMIs consume a significant portion of your income. Family responsibilities, insurance premiums, transportation, groceries and lifestyle expenses continue to rise. Add a few unexpected expenses, and even a high salary can begin to feel insufficient.
This is the financial challenge many middle- and high-income professionals face: their income grows, but their financial security doesn’t grow at the same pace.
The solution is not necessarily to earn more, work longer hours or invest in every opportunity that promises high returns. The solution begins with building better financial habits.
Here are three habits that can help you protect both your peace of mind and your financial future.
Habit 1: Plan Your Taxes Before the Financial Year Ends
One of the most common financial mistakes is treating income tax as a last-minute problem.
Many salaried employees wait until the end of the financial year to check their tax liability. By then, they may have limited time to review their options, organise documents or make appropriate financial decisions.
Tax planning should be part of your annual financial plan—not a last-minute activity.
What should you do?
1. Understand your actual take-home salary
Your annual CTC is not the same as the amount deposited into your bank account. Your CTC may include employer contributions, bonuses and other components that do not arrive as monthly take-home pay.
Review your salary structure and understand:
- Annual CTC and gross salary
- Monthly take-home salary
- Employee provident fund contributions
- Income tax deducted at source (TDS)
- Bonuses and variable compensation
- Other salary deductions
Build your monthly budget around your realistic take-home income rather than the headline salary.
2. Compare the old and new tax regimes
Eligible taxpayers should compare the old and new tax regimes based on their income, deductions and exemptions.
The new regime generally offers lower slab rates but allows fewer deductions. The old regime may be beneficial for some taxpayers who qualify for substantial deductions and exemptions.
Do not select a regime simply because a colleague or friend says it is better. Your circumstances may be different.
3. Keep your tax documents organised
Maintain your salary slips, Form 16, investment proofs where applicable, bank interest statements and other relevant documents.
Review your tax position periodically instead of waiting until the final weeks of the financial year.
The key lesson: Tax planning is about understanding and following the law while making informed decisions. It is not about hiding income or buying unnecessary financial products just to claim a deduction.
Habit 2: Pay Your Future Self Before Spending on Your Present Self
When your salary increases, it is tempting to upgrade everything.
You may move into a more expensive apartment, buy a new car, upgrade your phone, dine out more frequently or increase spending on holidays and shopping.
There is nothing wrong with enjoying the money you earn. The problem begins when every salary increase leads to an equal or greater increase in expenses.
This is known as lifestyle inflation.
For example, imagine that your monthly take-home pay increases by ₹20,000. If your new lifestyle consumes the entire increase, your salary has grown—but your ability to build wealth has not.
What should you do?
1. Automate your savings and investments
Instead of saving whatever remains at the end of the month, decide how much you can reasonably save after accounting for essential expenses and financial obligations.
Set up an automatic transfer after payday into appropriate savings or investment accounts.
Your allocation could include:
- An emergency fund
- Retirement savings
- Long-term investments
- Short-term goals such as a home, education or travel
The right allocation depends on your income stability, debts, goals, dependants and risk tolerance.
2. Increase savings when your income increases
Whenever you receive a salary hike or bonus, consider directing a portion of the increase toward savings, investments or debt repayment before upgrading your lifestyle.
For example, if your take-home pay increases by ₹10,000 per month, you might direct ₹5,000 toward your financial goals and use the remaining ₹5,000 to improve your lifestyle, provided your existing obligations are covered.
This is only an illustrative split—not a universal rule. Choose an amount that works for your circumstances.
3. Invest according to your goals and risk tolerance
Different financial goals require different approaches.
Money needed soon generally belongs in relatively stable, accessible options. Long-term goals may allow you to consider diversified investments, including equity funds, depending on your risk tolerance and time horizon.
Do not invest simply because a product is trending or someone promises exceptional returns.
Understand the risks, fees, liquidity and potential volatility before committing your money.
The key lesson: Wealth is not measured only by how much you earn or spend. It is also reflected in the assets you build and the financial choices available to you.
Habit 3: Protect Your Wealth Before Trying to Grow It
Many people focus on increasing their investment returns before protecting themselves against financial emergencies.
They may invest aggressively while carrying expensive personal loans, have no emergency savings or depend entirely on their next salary to pay their bills.
This creates financial vulnerability.
A medical emergency, job loss, family responsibility or unexpected repair can force someone to borrow money or sell investments at an unfavourable time.
Financial security begins with preparation.
What should you do?
1. Build an emergency fund
Start by calculating your essential monthly expenses, including housing, food, utilities, necessary transportation, loan payments and other unavoidable commitments.
A practical starting goal is to build an emergency fund covering three to six months of essential expenses. People with unstable income or significant family responsibilities may need a larger buffer.
For example, if your essential expenses are ₹50,000 per month, a three-to-six-month emergency fund would be ₹1.5 lakh to ₹3 lakh.
You do not need to build it overnight. Start with an affordable monthly contribution and gradually increase it.
Keep this money accessible and in relatively low-risk options rather than relying on volatile investments.
2. Review expensive debt
Not all debt is equally harmful, but high-interest debt can seriously damage your ability to build wealth.
List your outstanding loans, interest rates, minimum payments and remaining balances.
Prioritise expensive debt while continuing to make required payments on other loans. Before prepaying a loan, consider any applicable charges, liquidity needs and the loan’s terms.
Avoid taking new loans simply to maintain a lifestyle that your regular income cannot comfortably support.
3. Protect against major financial risks
Insurance can help protect your savings from certain large, unexpected costs.
Depending on your circumstances, review:
- Health insurance appropriate for your needs
- Adequate term life insurance if people depend on your income
- Personal accident or disability protection where relevant
- Existing employer-provided coverage and its limitations
Insurance is primarily for risk protection, not a substitute for an emergency fund or a complete investment strategy.
4. Avoid financial decisions driven by fear or greed
When markets rise, people often fear missing out. When markets fall, they may panic and sell. Others chase speculative trading schemes because they want to become wealthy quickly.
These behaviours can put long-term financial goals at risk.
Create an investment plan that matches your goals and review it at sensible intervals. Avoid borrowing money to speculate or investing in products you do not understand.
The key lesson: Your first financial priority should not always be maximising returns. It should be building a financial foundation strong enough to withstand unexpected events.
A Simple Monthly Financial System
You do not need a complicated spreadsheet or dozens of financial products to improve your financial life. Start with a system you can maintain consistently.
| Priority | What to do |
|---|---|
| 1. Essentials | Budget for housing, food, utilities and necessary expenses. |
| 2. Obligations | Pay taxes as applicable, EMIs and other required payments on time. |
| 3. Protection | Build emergency savings and review suitable insurance. |
| 4. Wealth building | Contribute regularly toward appropriate savings and investments. |
| 5. Lifestyle | Spend on things you value within your available budget. |
| 6. Review | Check your spending, savings, debt and goals every month. |
The order and amounts may vary depending on your circumstances. For example, someone carrying expensive debt may need to prioritise repayment alongside a starter emergency fund.
The objective is to give every rupee a purpose rather than wondering where your salary disappeared.
The 30-Day Action Plan
You can begin improving your financial habits this month without making drastic changes.
Week 1: Understand your money
- Review your monthly take-home income.
- List your essential and discretionary expenses.
- Write down all outstanding loans and their interest rates.
- Check your current savings and investments.
Week 2: Create your financial plan
- Prepare a realistic monthly budget.
- Review your income tax regime and likely tax liability.
- Decide on a manageable emergency-fund target.
- Identify unnecessary recurring expenses.
Week 3: Automate good habits
- Set up automatic transfers toward savings or investments.
- Start or increase your emergency-fund contribution.
- Prepare a repayment plan for expensive debt.
- Review your insurance coverage.
Week 4: Review and improve
- Compare planned spending with actual spending.
- Identify one habit that is weakening your financial position.
- Set one realistic savings or debt-reduction goal.
- Schedule a monthly financial review.
You do not have to become financially perfect in 30 days. You only need to begin making more deliberate decisions.
Final Thoughts: Financial Peace Is Also a Form of Wealth
Earning ₹20 lakh a year can provide opportunities, but it does not automatically guarantee financial freedom.
Your financial position depends on more than your salary. It also depends on your spending habits, tax planning, debt, savings, investments, responsibilities and ability to handle unexpected expenses.
You cannot control every change in the economy, every tax rule or every financial emergency. But you can improve how you prepare for them.
Remember these three habits:
- Plan your taxes instead of leaving them until the last minute.
- Pay your future self first instead of allowing every salary increase to become a new expense.
- Protect your financial foundation before chasing higher investment returns.
You do not need to look wealthy to become financially secure. You need a plan that helps you live within your means, prepare for uncertainty and steadily work toward your goals.
At The Finance Mastery Hub, we believe financial knowledge should help people make better decisions—not encourage shortcuts or unrealistic promises.
The goal is not just to earn more money. The goal is to build a life in which money supports your choices instead of controlling them.
Disclaimer
This article is for educational and informational purposes only. It does not constitute personalised tax, legal or investment advice. Tax treatment depends on applicable law and individual circumstances. Consider consulting a qualified professional before making significant financial decisions.