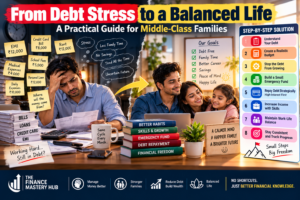

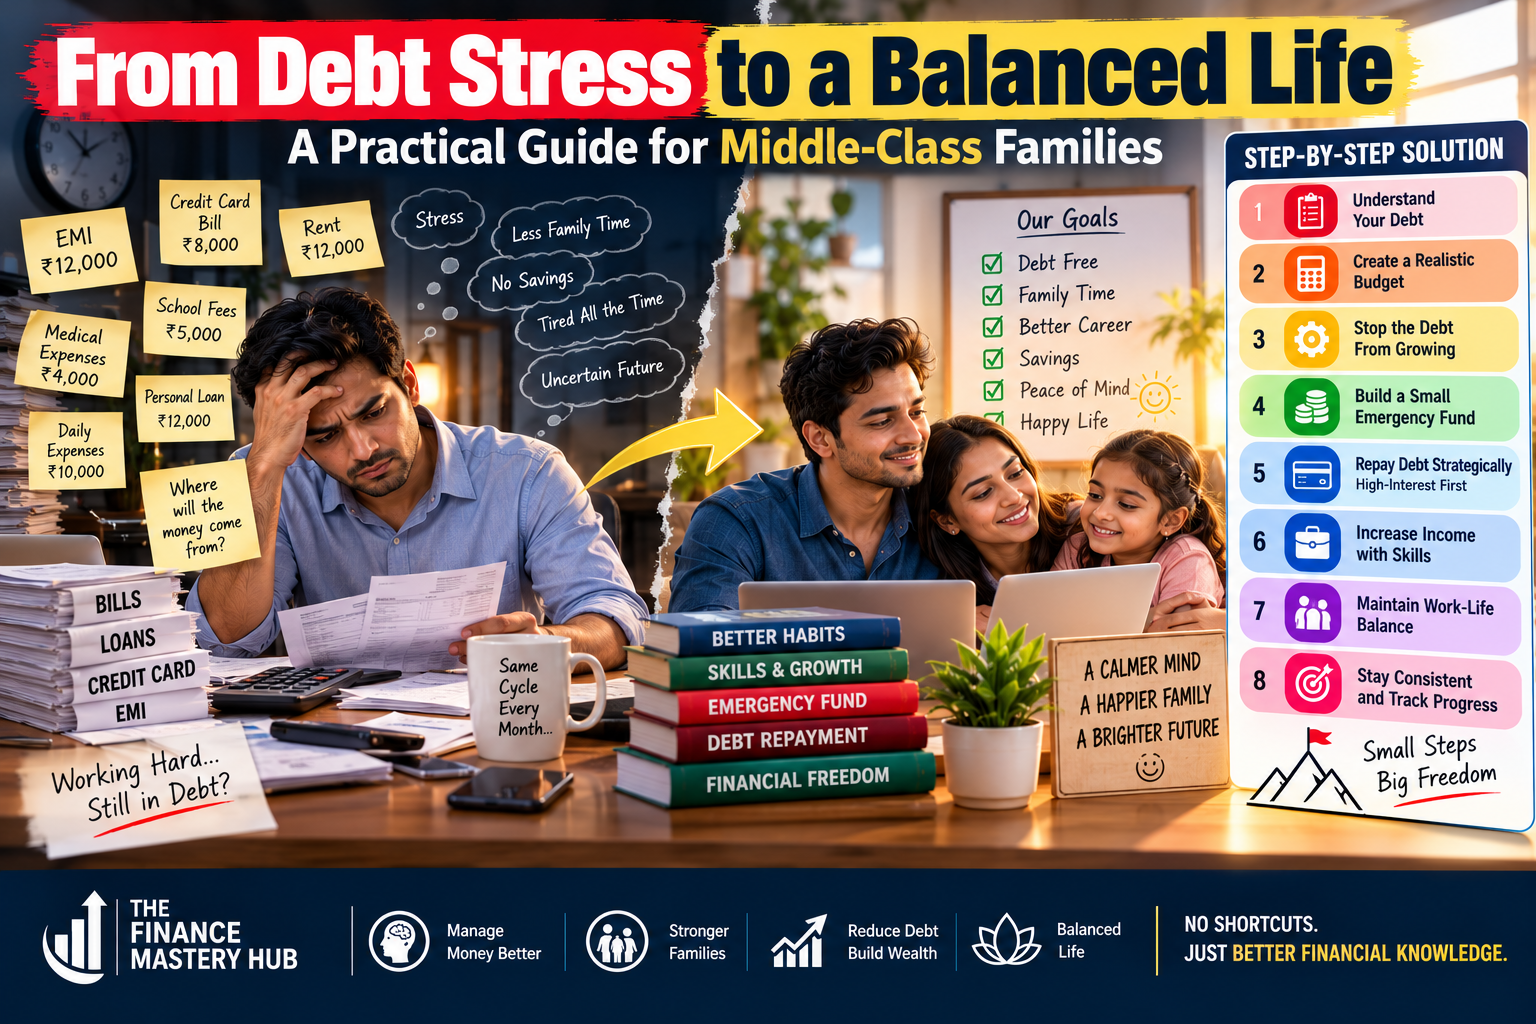
A relatable story about financial pressure, family responsibilities, and the journey toward financial freedom
By Vivek Singh | The Finance Mastery Hub
Introduction: When a Good Salary Still Isn’t Enough
Imagine waking up every morning, getting ready for work, checking your phone and seeing another reminder about an EMI payment.
You travel to the office, work for eight or nine hours, attend meetings, answer emails and return home exhausted. But even after working so hard, you cannot enjoy your evening because your mind is occupied with money.
You start calculating how much is left in your bank account. You think about your credit-card bill, personal loan, rent, groceries, children’s school fees and your parents’ medical expenses.
Your salary arrives, but within a few days, most of it disappears.
You want to take your family on a holiday, buy something useful for your home or simply enjoy a peaceful weekend. Instead, you tell yourself, “Maybe next month, when my financial situation improves.”
But next month arrives, and the same problem continues.
This is a reality for many middle-class families. Debt can gradually turn a person’s working life into a cycle of earning, paying EMIs and worrying about the next salary.
The problem is not always irresponsible spending. Sometimes it begins with a medical emergency, job loss, family responsibility, home purchase or a series of small financial decisions that become difficult to manage together.
The important question is not simply, “How can I earn more money?”
It is:
How can I reduce my debt without destroying my health, relationships, career and peace of mind?
Let’s understand this through a realistic story and a practical recovery plan.
1. Meet Rahul: A Middle-Class Professional Carrying Too Much Debt
Rahul is a fictional character, but his situation reflects challenges that many working professionals may recognise.
He is 34 years old and works in a private company. He lives with his wife and eight-year-old daughter. His parents also depend on him for some financial support.
Rahul has worked hard to build his career. He receives a regular salary, has a family and wants to provide a comfortable life for everyone.
A few years earlier, Rahul bought a motorcycle, purchased household items on credit and took a personal loan to cover several expenses. Later, an unexpected family medical expense forced him to use his credit card.
He planned to repay everything gradually.
But the balances did not fall as quickly as he expected. Interest charges, regular household expenses and new borrowing kept him stuck.
He began using his credit card to manage expenses before payday. When one EMI was due, he sometimes borrowed money from another source.
Eventually, his financial situation looked like this.
Rahul’s monthly financial position in below:
| Monthly income and expenses | Amount |
|---|---|
| Take-home salary | ₹75,000 |
| Rent | ₹12,000 |
| Groceries and household expenses | ₹10,000 |
| Electricity, phone and internet | ₹3,000 |
| Child’s education | ₹5,000 |
| Transport and fuel | ₹4,000 |
| Parents’ support and medical expenses | ₹4,000 |
| Other essential expenses | ₹3,000 |
| Personal loan EMI | ₹12,000 |
| Vehicle loan EMI | ₹5,000 |
| Credit-card payment | ₹8,000 |
| Total monthly outflow | ₹66,000 |
| Amount remaining | ₹9,000 |
At first glance, Rahul has ₹9,000 left every month. But that amount must also cover irregular expenses, repairs, emergencies, clothing and other costs that do not arrive on a predictable schedule.
One unexpected bill can eliminate the surplus.
Now consider the emotional impact.
Rahul checks his bank balance several times a day. He avoids discussing money with his wife because he feels embarrassed. At work, he struggles to concentrate. At home, he becomes impatient over small things.
His daughter asks him to join her for an evening game, but he says he is busy. Sometimes he is genuinely tired. Other times, he is physically present but mentally occupied with debt.
Rahul is earning money, but he no longer feels in control of his life.
His problem is not just financial. It is affecting his work, family and personal well-being.
2. The First Turning Point: Rahul Stops Hiding From His Numbers
One evening, Rahul receives another credit-card statement.
He feels the familiar pressure in his chest. His first reaction is to close the message and forget about it.
But this time, he makes a different decision.
He sits down with a notebook and writes every outstanding loan on one page.
He records the amount remaining, interest rate, minimum payment, EMI and due date for each debt.
He also checks his bank statements to understand where his salary goes.
For the first time, he sees the complete picture.
He realises that he has been making payments without following a clear strategy. He has also been using credit to cover expenses that his regular income cannot comfortably support.
The numbers are uncomfortable, but they give him something valuable: clarity.
The first step toward reducing debt is to understand exactly what you owe.
Avoiding the problem may provide temporary emotional relief, but it does not change the amount owed or the interest accumulating.
Your first action
Create a debt inventory like this:
| Debt | Outstanding balance | Interest rate | Required monthly payment |
|---|---|---|---|
| Credit card | ₹1,20,000 | 36% annually, illustrative | ₹8,000 currently budgeted |
| Personal loan | ₹3,00,000 | 15% annually, illustrative | ₹12,000 EMI |
| Vehicle loan | ₹1,50,000 | 10% annually, illustrative | ₹5,000 EMI |
| Total | ₹5,70,000 | — | ₹25,000 |
These balances and rates are illustrative, not actual loan quotations. Rahul must check his agreements and current statements to confirm the real figures.
Notice that Rahul has ₹5.7 lakh of debt. His total monthly payments are ₹25,000, before his other household expenses.
Writing these numbers down does not immediately eliminate the debt. It gives him a starting point for making informed decisions.
3. Step One: Stop the Debt From Growing
Rahul’s first objective is not to repay every loan as quickly as possible.
It is to stop his financial position from getting worse.
If he continues using his credit card to cover routine household expenses, every repayment may be offset by new borrowing.
He therefore makes three changes.
First, he stops unnecessary credit-card spending
Rahul removes saved credit-card details from shopping apps and stops buying non-essential items on instalments.
He does not cancel essential spending. Instead, he moves everyday purchases into a realistic monthly budget.
Second, he avoids taking new loans to maintain his lifestyle
He postpones buying a new phone, upgrades to his home entertainment system and expensive holidays.
These are not permanent bans. They are temporary decisions made while his financial position is under pressure.
Third, he contacts his lenders when necessary
If he cannot meet a payment, he does not simply ignore calls or wait until the account becomes seriously overdue.
He contacts the lender through official channels and asks about the available repayment options, hardship arrangements or restructuring possibilities.
Any proposed change should be reviewed carefully. A lower EMI can mean a longer repayment period and more total interest. Loan restructuring, settlement and refinancing are not automatically the best solutions in every case.
The goal is to stop borrowing from the future to pay for the present.
4. Step Two: Create a Budget That Works in Real Life
Many people make budgets that look excellent on paper but are impossible to follow.
They allocate every rupee to bills, savings and loan repayment, leaving nothing for an unexpected expense or a small amount of personal enjoyment.
When the plan becomes too restrictive, they abandon it and return to their old habits.
Rahul decides to build a realistic budget instead.
He reviews his expenses and identifies a few areas where he can reduce spending without compromising his family’s basic needs.
For example, he compares grocery prices, reduces food delivery, reviews unnecessary subscriptions and plans his transport expenses more carefully.
He also discusses the situation with his wife. Together, they agree to postpone certain purchases and review spending once a week.
Rahul’s revised monthly budget
| Category | Before | Revised target |
|---|---|---|
| Rent | ₹12,000 | ₹12,000 |
| Groceries | ₹10,000 | ₹9,000 |
| Utilities and communication | ₹3,000 | ₹3,000 |
| Education | ₹5,000 | ₹5,000 |
| Transport | ₹4,000 | ₹3,500 |
| Parents’ support and medical expenses | ₹4,000 | ₹4,000 |
| Other essential expenses | ₹3,000 | ₹2,500 |
| Personal loan EMI | ₹12,000 | ₹12,000 |
| Vehicle loan EMI | ₹5,000 | ₹5,000 |
| Credit-card payment budget | ₹8,000 | ₹8,000 |
| Total | ₹66,000 | ₹64,000 |
| Monthly amount remaining | ₹9,000 | ₹11,000 |
The revised budget frees up ₹2,000 per month through modest reductions.
Rahul does not assume that he can eliminate every unexpected expense. He uses the extra room in his budget to begin building a small cash buffer and, once that buffer is adequate, direct more money toward expensive debt.
The exact allocation depends on his actual loan terms, essential expenses and emergency savings.
The lesson
A budget should not punish you for having a life.
It should help you understand which expenses are necessary, which can be adjusted and how much money you can realistically use to reduce debt.
5. Step Three: Build a Small Emergency Buffer
Rahul initially believes that every spare rupee should go toward debt repayment.
That sounds sensible, especially when his credit-card interest rate is high. However, if he has no accessible savings, even a small emergency could force him to borrow again.
He decides to build a modest starter emergency buffer while continuing to make all required loan payments.
He begins with a target of ₹20,000, adjusted to his circumstances.
He keeps the money accessible and does not invest it in volatile assets.
Once the buffer is established, he can direct more of his available surplus toward high-interest debt while rebuilding his emergency savings gradually.
The longer-term goal is to build an emergency fund covering several months of essential expenses, often three to six months as a starting benchmark.
That larger target may take time. Rahul does not need to wait until he has a complete emergency fund before beginning to reduce his expensive debt.
The key is balance: maintain enough liquidity to handle foreseeable emergencies without unnecessarily prolonging costly borrowing.
6. Step Four: Repay Debt Using a Clear Strategy
Rahul now understands his debts, has a more realistic budget and has started building a financial buffer.
His next task is to decide which debt to repay first.
Two common approaches are the debt avalanche and the debt snowball.
Debt avalanche: Prioritise the highest interest rate
Under this approach, you make the required payments on all debts and direct extra money toward the debt with the highest interest rate.
This generally reduces interest costs compared with prioritising lower-rate debts, assuming other factors are equal and you follow the plan.
For Rahul, that may mean prioritising the credit card if its actual interest rate is significantly higher than the personal and vehicle loans.
Debt snowball: Prioritise the smallest balance
Under this approach, you make the required payments on all debts and direct extra money toward the smallest outstanding balance first.
Clearing a small debt can provide motivation and simplify your monthly obligations. However, it can cost more in interest if you leave a much higher-rate debt outstanding.
Which strategy should Rahul choose?
Because his credit-card debt carries a high illustrative interest rate, the avalanche approach is likely to be more cost-effective if the actual terms confirm that rate and he can maintain the plan.
He keeps paying the required amounts on his personal and vehicle loans and directs additional available money toward the credit card.
He does not miss other payments to accelerate the credit-card repayment.
An illustrative repayment scenario
Suppose Rahul can direct an additional ₹6,000 per month toward his credit-card balance after meeting required payments, maintaining his starter buffer and covering realistic household expenses.
He would then pay his usual budgeted ₹8,000 toward the card plus the extra ₹6,000, for a total monthly payment of ₹14,000.
At an illustrative 36% annual interest rate, the monthly interest rate would be approximately 3% before considering the card’s actual calculation method, fees and other terms.
A ₹1,20,000 balance could initially generate roughly ₹3,600 of interest for a month under this simplified approximation.
That means a ₹14,000 payment would not reduce the principal by the full ₹14,000.
The exact repayment duration and total cost depend on the card’s terms, transaction history, fees, payment timing and any additional spending.
Rahul therefore checks the statement and asks the card issuer for a clear explanation of interest and repayment calculations.
Important: The extra ₹6,000 is only an example. Rahul should not promise this amount unless his actual budget supports it. If his available surplus is smaller, he can begin with a smaller additional payment and increase it when his finances improve.
7. Step Five: Protect Your Work-Life Balance While Repaying Debt
This is where many debt-reduction plans fail.
People become so focused on earning more and paying loans that they sacrifice sleep, family time, health and emotional stability.
They work late every day, accept every extra assignment and stop taking breaks. They tell themselves that life will begin again after all their debt has been repaid.
But financial recovery may take months or years.
You need a plan that you can follow without exhausting yourself.
Rahul changes his daily routine
He makes four practical changes.
1. He sets a fixed time to review money matters.
Instead of checking his bank balance throughout the day, Rahul sets aside 20 minutes twice a week to review transactions, bills and repayment progress.
He checks urgent payment notifications when necessary, but he no longer spends every spare moment recalculating the same numbers.
2. He protects his sleep.
He recognises that tiredness makes it harder to concentrate at work and make thoughtful decisions.
He aims for a consistent sleep schedule rather than staying awake every night worrying about debt.
3. He keeps small moments of family time.
Rahul cannot afford an expensive holiday at the moment, but he can still spend time with his daughter, take a walk with his wife or share a simple meal with his parents.
He stops treating every low-cost activity as a financial failure.
4. He creates boundaries around extra work.
Rahul explores opportunities for a promotion or better-paying job, but he does not immediately accept every possible side project.
He evaluates whether additional work is sustainable, how much income it may generate after expenses and taxes, and whether it will interfere with his primary job or health.
Extra income can help, but exhaustion is not a financial strategy.
A realistic weekday schedule
| Time | Activity |
|---|---|
| Morning | Wake up, prepare for the day and review priorities |
| Working hours | Focus on primary job responsibilities |
| After work | Take a short break and spend time with family |
| 20 minutes on planned days | Review expenses or learn a useful career skill |
| Evening | Dinner, relaxation and family time |
| Before bed | Prepare for tomorrow and wind down |
This is only an example. Shift workers, parents of young children and people with long commutes will need a different schedule.
The principle is to give work, financial planning, rest and relationships a place in your routine.
8. Step Six: Increase Income Without Depending on Risky Shortcuts
Reducing expenses has limits. There may be a point when Rahul cannot cut much more without affecting essential needs.
At that stage, improving his income may become an important part of the recovery plan.
He starts by reviewing his career rather than looking for quick-money schemes.
He identifies skills that could improve his prospects for a promotion or a better-paying role. He updates his CV, practises interviews and explores opportunities that fit his experience.
If he considers freelance work or a side business, he evaluates the real costs, time commitment, tax obligations and likelihood of receiving payment.
He does not assume that additional income is guaranteed.
What should you do?
- Identify a skill that is valuable in your current profession.
- Set aside regular, manageable time for learning.
- Review salary opportunities and market requirements.
- Prepare for interviews and internal promotion discussions.
- Evaluate side-income ideas before spending money to start them.
- Direct a predetermined portion of additional take-home income toward debt repayment.
Avoid borrowing more money to trade, speculate or join schemes that promise guaranteed returns.
When you are already under financial pressure, a high-risk decision can make recovery more difficult.
The objective is to increase earning capacity through skills, career development and realistic opportunities—not desperation.
9. Step Seven: Talk to Your Family Instead of Carrying Everything Alone
Rahul initially hides his debt because he believes that discussing it will make him look unsuccessful.
But secrecy creates more pressure. His wife does not understand why he keeps refusing reasonable family plans, and Rahul feels increasingly isolated.
Eventually, he explains the situation calmly.
He shares the total debt, the monthly payments and the plan he wants to follow. They agree on a temporary spending limit, a monthly review and a list of expenses that cannot be compromised.
They also agree not to blame each other for every past decision.
This changes the problem from a private burden into a shared financial challenge.
Not every family conversation will be easy, particularly if there are disagreements or concerns about financial safety. Choose an appropriate time, share accurate information and focus on the next steps.
If debt involves a co-borrower, guarantor or joint account, make sure everyone understands the relevant legal and financial obligations.
Financial honesty can reduce confusion, but it should be supported by a practical plan.
10. Step Eight: Avoid Debt-Relief Mistakes That Make Things Worse
When people are under pressure, they may accept the first offer that promises immediate relief.
Be careful with the following options.
Taking another loan without comparing the full cost
A consolidation loan may help if it offers a lower overall cost, manageable payments and suitable terms.
However, a lower EMI alone does not prove that a loan is cheaper. A longer repayment period may increase total interest, and fees may reduce the benefit.
Compare the interest rate, fees, tenure, total repayment and consequences before proceeding.
Settling a debt without understanding the consequences
A settlement may resolve a debt under agreed terms, but it can have consequences for credit history and future borrowing. Obtain the terms in writing and understand how the account will be reported.
Do not assume that settlement is always better than repayment or restructuring.
Ignoring lender communication
Ignoring notices or payment reminders does not eliminate the obligation.
If you cannot pay, communicate through official lender channels, ask about available options and keep copies of all correspondence.
Paying a suspicious debt-relief agent upfront
Be cautious of anyone promising guaranteed debt elimination, asking for sensitive credentials or demanding upfront fees without clear documentation.
Verify the organisation independently and never share banking passwords or one-time passwords.
Using every rupee to repay debt
Repaying expensive debt is important, but having no money available for essentials or emergencies can lead to fresh borrowing.
Build a sustainable plan that accounts for both debt reduction and basic financial resilience.
11. A Practical 90-Day Debt Recovery Plan
Rahul decides to focus on the next 90 days rather than imagining the entire repayment journey at once.
Days 1–30: Understand and stabilise
- List every debt, interest rate, minimum payment and due date.
- Review income and essential expenses.
- Stop unnecessary new borrowing.
- Create a realistic budget.
- Contact lenders early if any payment is at risk.
- Begin a starter emergency buffer if possible.
Goal: Understand the full financial picture and stop the situation from deteriorating.
Days 31–60: Start the repayment system
- Make all required payments on time where possible.
- Choose a repayment strategy.
- Direct an affordable extra amount toward the priority debt.
- Review recurring expenses.
- Discuss the plan with affected family members.
- Protect sleep and family time.
Goal: Establish a repayment habit that can continue beyond one month.
Days 61–90: Review and improve
- Compare current balances with the starting balances.
- Check whether interest and fees are reducing your progress.
- Adjust the budget if expenses have changed.
- Explore realistic career or income opportunities.
- Increase the repayment amount only if the budget supports it.
- Plan the next 90 days.
Goal: Make measurable progress and refine the plan based on actual results.
Debt reduction is not always linear. Unexpected expenses or changes in income can slow progress. If that happens, review the plan rather than treating one difficult month as complete failure.
12. What Happens After Rahul Starts Making Progress?
After several months, Rahul begins to notice changes.
He has a clearer understanding of his debt. He is no longer using his credit card casually to bridge everyday spending. His family knows the plan, and they review their budget together.
His debt has not disappeared. He still has repayments to make and financial goals to work toward.
But he is no longer treating every financial problem as an emergency.
He knows which debt he is prioritising, how much he can afford to pay and what he will do if an unexpected expense occurs.
He is also more deliberate about his career. Instead of searching desperately for quick income, he focuses on developing skills that may improve his earning potential.
Most importantly, he begins to reconnect with his life outside money.
He spends time with his daughter. He takes walks. He stops checking his bank balance every few minutes. He understands that financial recovery is a process, not a single dramatic event.
Rahul’s biggest achievement is not that he becomes debt-free overnight.
It is that he begins to regain control over his decisions.
13. The Most Important Lessons for Middle-Class Families
Rahul’s story highlights several practical lessons.
Debt should be measured, not hidden. You cannot create an effective repayment plan without knowing the outstanding balances and costs.
A budget must be realistic. A plan that ignores normal life expenses is unlikely to last.
High-interest debt needs attention. After meeting required payments and maintaining appropriate liquidity, prioritising the highest-cost debt can reduce the interest burden.
Career growth is more sustainable than desperate risk-taking. Better skills and suitable opportunities may improve income without exposing the household to unnecessary speculation.
Family time and health are not rewards reserved for debt-free people. They remain important while you are working toward financial stability.
Progress is more useful than perfection. A manageable plan followed consistently is often more effective than an extreme plan abandoned after a few weeks.
Conclusion: Your Debt Is a Problem to Solve, Not Your Identity
Many middle-class people carry financial responsibilities that others never see.
They work hard, support their parents, raise children, pay EMIs and try to build a better future. Sometimes, despite their best intentions, debt becomes overwhelming.
If you are in this situation, you do not need to solve everything today.
Start by writing down what you owe. Build a realistic budget. Stop unnecessary borrowing. Maintain essential payments, create an appropriate emergency buffer and prioritise expensive debt. Seek help from your lenders or a qualified professional when the situation requires it.
At the same time, protect your health, relationships and ability to work. Your financial plan should support your life, not consume every part of it.
You may not be able to control every emergency, expense or change in income. But you can begin to control the decisions you make from today onward.
Remember: the goal is not simply to pay off your loans. It is to build a financial life in which you can earn, repay, save, rest and live with greater peace of mind.
At The Finance Mastery Hub, we believe financial knowledge should help people make informed decisions, manage money responsibly and build a better future—without unrealistic promises or shortcuts.
Disclaimer
This article is for educational purposes only. The characters and financial figures are fictional and intended to illustrate common situations. Debt repayment options depend on actual loan terms, interest rates, income and household needs. Consider speaking with your lender or a qualified financial professional for guidance specific to your circumstances.