
By Vivek Singh | The Finance Mastery Hub
Introduction: Is GST Becoming Easier for Indian Freelancers?
Imagine you are a freelance graphic designer, software developer, digital marketer, financial consultant or content writer in India.
You work from your home, provide services to clients and receive payments from different countries. Your business is growing, but you have questions:
- Do I need GST registration?
- Should I charge GST to Indian clients?
- What happens when I receive payments from international clients?
- Can I export services without paying IGST upfront?
- What are the benefits of filing a Letter of Undertaking (LUT)?
- Have the GST rules changed in 2026?
These are important questions because understanding GST can help freelancers avoid unnecessary compliance problems and manage their business finances more effectively.
The 57th GST Council meeting, held on 8 October 2026, recommended several reforms relating to registration, refunds, exports and compliance procedures. Some of these recommendations could create opportunities for Indian service providers working with international clients.
However, it is important to understand one thing: there is no new blanket GST exemption or special registration threshold announced exclusively for freelancers.
The opportunity lies in understanding the existing GST framework and preparing for the changes that are actually relevant to your business.
Let’s understand everything through practical examples.
1. What Is GST for Freelancers?
GST stands for Goods and Services Tax. It is an indirect tax applicable to eligible supplies of goods and services in India.
If you work independently and provide services in exchange for payment, your activity may qualify as a supply of services under GST.
For example:
- A graphic designer creates logos for businesses.
- A software developer builds applications for customers.
- A digital marketer manages advertising campaigns.
- A content writer prepares articles for companies.
- A consultant provides professional advice.
- A video editor creates promotional videos.
Depending on the nature of the service, location of the customer, turnover and applicable GST provisions, you may have GST registration and tax obligations.
Freelancing does not automatically make you exempt from GST. Your actual business activities and circumstances determine your position.
2. What Changed in the 57th GST Council Meeting in 2026?
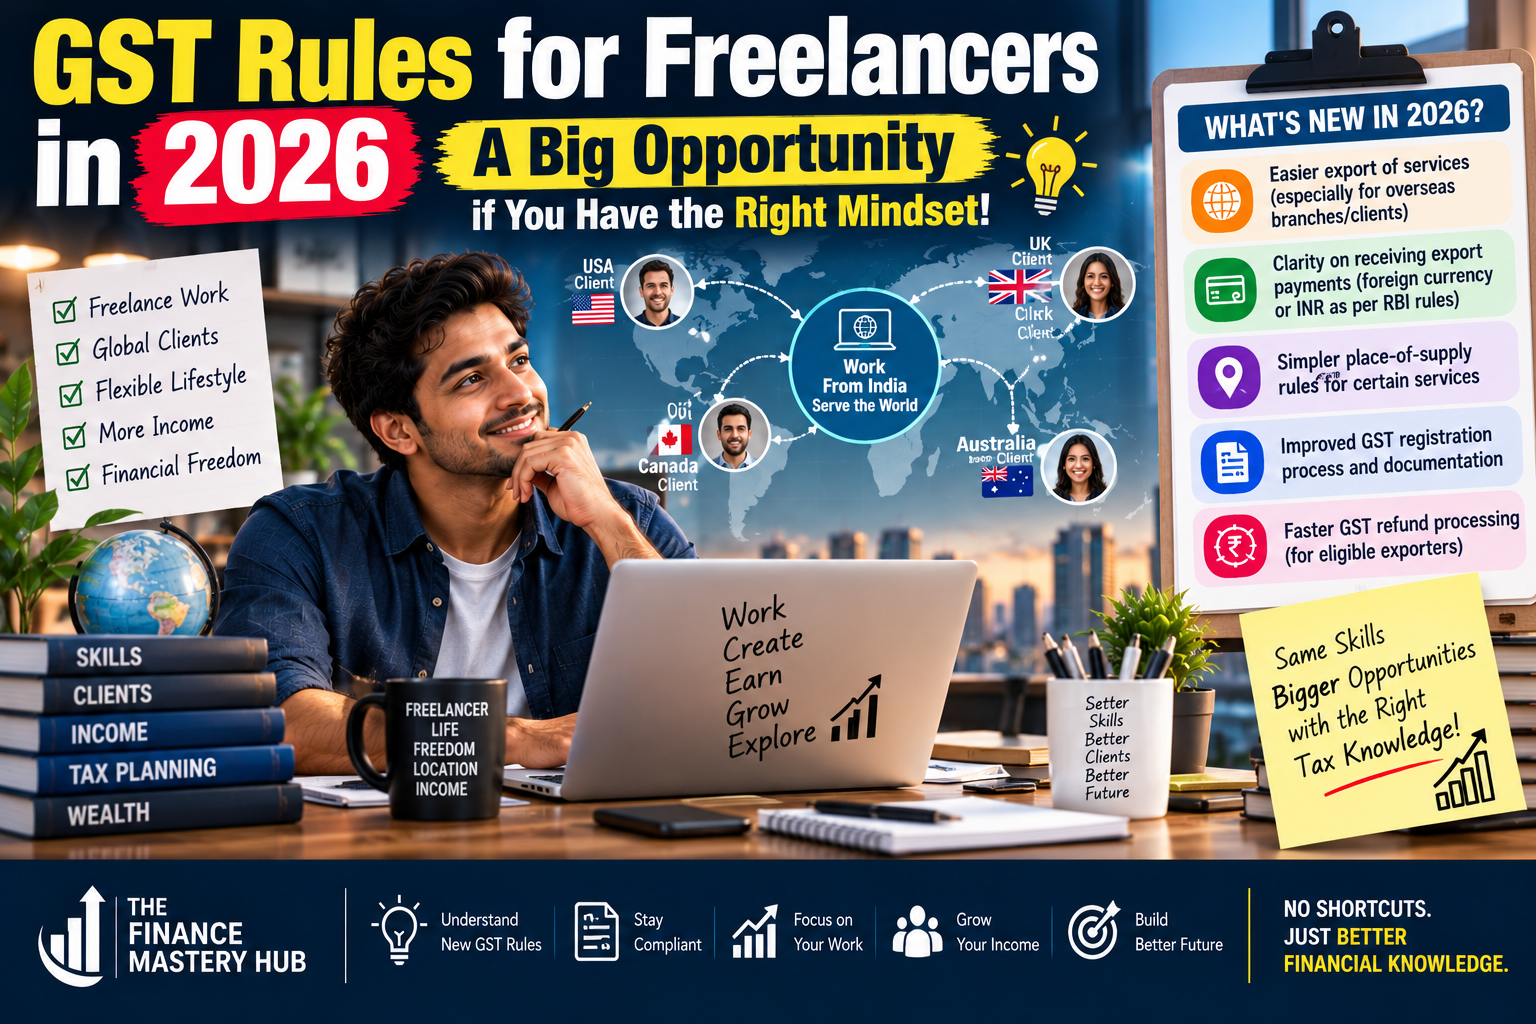
The 57th GST Council meeting recommended reforms mainly focused on simplifying GST procedures, improving refunds, clarifying export-related provisions and reducing compliance difficulties.
Some recommendations are relevant to freelancers, particularly those who provide services internationally.
Here are the key points.
Change 1: Proposed support for export of services
One important recommendation relates to the definition of export of services under the Integrated Goods and Services Tax (IGST) Act.
The Council recommended removing the condition under Section 2(6)(v) that the supplier and recipient must not be establishments of a distinct person.
Why does this matter?
Consider an Indian company or service provider working with an overseas office or branch. Under the existing framework, transactions between distinct establishments of the same legal person can create difficulties in qualifying as exports of services.
The proposed amendment is intended to facilitate export-related treatment and refunds for certain Indian service providers supplying services to or through foreign offices or branches.
Who may benefit?
- Indian service providers with overseas branches.
- Businesses operating through international establishments.
- Certain service exporters with cross-border business structures.
This is not an automatic benefit for every freelancer who receives money from abroad. The amendment must be implemented, and the applicable conditions must still be satisfied.
Change 2: Clarification about receiving export payments
The Council also recommended clarification regarding receipt of export payments in foreign currency or Indian rupees where permitted by the Reserve Bank of India (RBI).
This is relevant because freelancers sometimes receive payments from overseas clients through international payment platforms or banking channels.
The important point is that payment in Indian rupees is not automatically acceptable in every export transaction. The payment arrangement must satisfy the applicable RBI requirements.
What should freelancers do?
- Keep invoices issued to overseas clients.
- Maintain bank statements and payment-platform records.
- Preserve foreign inward remittance or other applicable payment evidence.
- Check the permitted payment route and relevant RBI requirements.
- Confirm the export-of-services conditions before claiming zero-rated treatment.
Change 3: Proposed place-of-supply clarification for certain services
The Council recommended removing Section 13(3)(a) of the IGST Act for services where goods are made physically available to the supplier to provide the service.
The intention is to apply the general place-of-supply rule under Section 13(2) in the specified circumstances.
This could help certain Indian service providers working on goods supplied by overseas customers.
For example, an Indian specialist may receive a foreign customer’s equipment for a particular testing or repair service.
The proposed change may affect the GST treatment of certain such transactions.
This is a specialised provision. It should not be interpreted as changing the place-of-supply rules for every ordinary freelance service.
Change 4: Improvements in GST registration
The Council recommended clearer registration documentation, an improved GST REG-01 application and a more user-friendly GST portal.
It also recommended simpler procedures for certain registration amendments.
These improvements are intended to reduce unnecessary queries and make registration more predictable.
For freelancers planning to expand their business, better registration procedures may make compliance easier.
Change 5: Faster refund processing
The Council recommended more automated processing of eligible GST refunds.
For qualifying zero-rated supplies, the proposed system includes provisional sanction of 90% of eligible refund claims based on system risk assessment.
This may be useful for eligible registered exporters who have accumulated input tax credit.
However, this does not mean that every freelancer automatically receives a 90% refund. Eligibility, documentation, risk checks and applicable legal provisions continue to matter.
These are Council recommendations and must be implemented through the required legal changes and notifications. <Cite refs={[“turn471871view0″,”turn422355search0”]}/>
3. Does Every Freelancer Need GST Registration?
No. GST registration depends on aggregate turnover and other applicable conditions.
For many service providers, the general registration threshold is ₹20 lakh in aggregate annual turnover. A lower threshold may apply in specified states and situations.
Importantly, aggregate turnover is calculated on an all-India basis for persons having the same PAN. It includes taxable supplies, exempt supplies, exports and inter-state supplies, subject to the statutory exclusions.
Certain compulsory-registration provisions and exemptions can also affect the result.
Example: Freelancer earning ₹12 lakh annually
Suppose Priya is a freelance content writer based in Uttar Pradesh.
Her annual freelance turnover is ₹12 lakh. She provides services to Indian clients and has no other business turnover under the same PAN.
If no compulsory-registration provision or other exception applies, she would generally remain below the ₹20 lakh service-provider threshold.
She should still maintain proper income and business records.
Example: Freelancer earning ₹25 lakh annually
Now suppose Priya’s freelance business grows and her aggregate turnover reaches ₹25 lakh.
She crosses the general ₹20 lakh threshold and would ordinarily need to obtain GST registration, subject to applicable provisions and exemptions.
She should not wait until the end of the financial year if her turnover crosses the applicable threshold. Registration obligations arise according to the law and relevant timelines.
Important: Export turnover is also included in aggregate turnover. A freelancer cannot automatically ignore international client receipts when calculating the GST registration threshold.
The threshold is not a separate limit for each customer or payment platform. <Cite refs={[“turn604918search0″,”turn604918search1″,”turn604918search2”]}/>
4. What If You Work With International Clients?
This is one of the most important areas for Indian freelancers.
Suppose you are a software developer in India and provide development services to a company in the United States.
You receive ₹30 lakh during the financial year from your overseas clients.
Can you simply treat all these receipts as tax-free exports?
No. First, you must determine whether your services qualify as an export of services under GST law.
Under the existing general definition, the following conditions must be satisfied:
- The supplier of the service is located in India.
- The recipient of the service is located outside India.
- The place of supply is outside India.
- Payment is received in convertible foreign exchange or Indian rupees wherever permitted by the RBI.
- The supplier and recipient are not merely establishments of a distinct person, subject to the proposed amendment discussed earlier.
All relevant conditions must be examined for the actual transaction.
Practical example
A freelance software developer in India provides application-development services to a company in the United States.
The developer:
- Works from India.
- Has a contract with the US company.
- Issues invoices for software-development services.
- Receives payment through a permitted banking channel.
- Maintains the required supporting documents.
If the transaction satisfies all the statutory conditions for export of services, it may qualify as a zero-rated supply.
But if the overseas customer is merely an intermediary, the actual recipient and place-of-supply analysis may be different.
Similarly, a foreign payment alone does not prove that a transaction qualifies as an export.
5. What Is LUT and Why Is It Important for Freelancers?
LUT stands for Letter of Undertaking.
It is a declaration filed by an eligible registered taxpayer that allows qualifying zero-rated supplies to be made without payment of IGST upfront, subject to applicable conditions.
The prescribed form is GST RFD-11.
This can be useful for registered freelancers and businesses exporting eligible services.
Example: Freelancer working with a foreign client
Suppose Arjun is a GST-registered freelance graphic designer in India.
He provides eligible export services worth ₹5 lakh to a foreign client.
If the transaction qualifies as an export of services and Arjun has furnished a valid LUT, he can generally issue the export invoice without charging IGST upfront, subject to the applicable rules.
This helps avoid an upfront IGST payment on qualifying exports.
It does not mean that the freelancer is exempt from all GST compliance. Registration, invoicing, returns, documentation and other applicable requirements continue to apply.
How to file LUT
- Visit the official GST portal.
- Log in using your GST credentials.
- Select Services.
- Select User Services.
- Choose Furnish Letter of Undertaking (LUT).
- Select the relevant financial year.
- Complete the required declarations and details.
- Submit the application using the prescribed verification process.
- Save the acknowledgement for your records.
A fresh LUT is generally furnished for each financial year.
The GST portal provides the official filing instructions for Form GST RFD-11. <Cite refs={[“turn604918search4″,”turn604918search32”]}/>
6. How Much GST Should Freelancers Charge?
There is no single GST rate that applies to every freelance service.
The applicable rate depends on the nature and classification of the service and the relevant notification.
Many commonly supplied domestic professional and business services are taxed at 18%, but you should confirm the applicable SAC classification and rate before issuing an invoice.
Example: Indian client
Suppose a freelance digital marketer provides a taxable service to an Indian business.
| Particulars | Amount |
|---|---|
| Professional service fee | ₹50,000 |
| Illustrative GST at 18% | ₹9,000 |
| Total invoice value | ₹59,000 |
The ₹9,000 GST component is tax collected for payment to the government, subject to applicable rules. It should not be treated as the freelancer’s personal income.
Example: Eligible export service under LUT
Suppose the same freelancer provides a qualifying export service worth ₹50,000.
| Particulars | Amount |
|---|---|
| Export service value | ₹50,000 |
| IGST charged under valid LUT | ₹0 |
| Invoice total | ₹50,000 |
This example assumes the supply satisfies the export-of-services conditions and the freelancer has a valid LUT.
Zero-rated treatment is not the same as an ordinary GST exemption. Eligible registered exporters may also be entitled to refunds of unutilised ITC, subject to the applicable conditions and procedures.
7. A Step-by-Step GST Compliance Plan for Freelancers
Now let’s turn the information into an action plan.
Whether you are a designer, consultant, developer, content writer or digital marketer, follow these steps.
Step 1: Calculate your annual turnover
Maintain a record of all business receipts and supplies.
Include domestic and export supplies when calculating aggregate turnover.
Do not calculate the GST threshold using only the payments received in one bank account or from one client.
Step 2: Identify your client location
Maintain a separate record of:
- Indian clients.
- Overseas clients.
- Client legal names and addresses.
- Contract details.
- Nature of services provided.
- Invoice values and payment details.
This helps you identify which transactions need a domestic GST analysis and which may qualify as exports.
Step 3: Check your registration requirement
Review the applicable turnover threshold and any compulsory-registration provisions.
If you cross the threshold, obtain registration within the required timeline.
If your position is complicated because you supply services across states or internationally, obtain professional advice.
Step 4: Use proper invoices
Your invoices should contain the applicable details required under GST law.
Maintain consistent invoice numbers, customer information, service descriptions, taxable values and tax details.
For export invoices, include the required export endorsement and other prescribed particulars, depending on whether the supply is made under LUT or on payment of IGST.
Step 5: Apply for LUT if eligible
If you are registered and make qualifying zero-rated supplies, examine whether furnishing LUT is appropriate for your business.
Do not issue a zero-IGST export invoice under LUT without satisfying the required procedure.
Step 6: Maintain payment evidence
Keep bank statements, payment-platform statements, contracts and other supporting documents.
For export services, confirm that the payment method satisfies the applicable requirements.
Step 7: File returns on time
Registered freelancers must comply with the applicable return-filing requirements.
Depending on their registration and eligibility, they may have different filing frequencies.
Reconcile sales records, purchases, eligible ITC and GST liabilities before filing.
Step 8: Review your GST position every quarter
As your business grows, your GST position may change.
Review turnover, client locations, new services, payment methods and registration obligations regularly.
Do not wait for an annual tax review to identify a compliance problem.
8. Three Common GST Mistakes Freelancers Should Avoid
Mistake 1: Assuming international payments are automatically tax-free
Receiving money from a foreign client does not automatically make a transaction an export of services.
Solution: Check all export conditions, particularly the recipient, place of supply and payment requirements.
Mistake 2: Ignoring exports while calculating turnover
Some freelancers calculate their registration threshold only on domestic income.
Solution: Remember that exports are generally included in aggregate turnover. Maintain an all-India PAN-based turnover record.
Mistake 3: Charging GST without checking the applicable rate
Different professional services may have different classifications and tax treatments.
Solution: Identify the correct service classification and verify the applicable rate before issuing invoices.
9. The Opportunity: Turn Freelancing Into a Proper Business
GST knowledge is not just about avoiding penalties. It can help you build a more organised and professional freelance business.
Imagine two freelancers.
The first freelancer accepts projects, sends informal payment requests and maintains incomplete records.
The second freelancer:
- Uses written contracts.
- Issues proper invoices.
- Maintains a business bank-record trail.
- Understands domestic and export transactions.
- Tracks annual turnover.
- Plans tax payments.
- Maintains a proper accounting system.
Both may have similar technical skills, but the second freelancer is better prepared to manage business growth.
International clients often expect professional documentation, clear payment terms and reliable communication.
A well-managed financial system can support credibility and make it easier to expand into larger projects.
The opportunity is not simply that the GST rules may become easier. It is that you can use financial knowledge to build a stronger business.
10. Your 30-Day Action Plan
Here is a simple plan to put everything into practice.
Week 1: Understand your business
- List all your freelance services.
- Identify domestic and overseas clients.
- Calculate your aggregate turnover.
- Review your existing invoices and contracts.
Week 2: Understand GST requirements
- Check whether GST registration is required.
- Identify the applicable tax classification for your services.
- Review the export-of-services conditions.
- Understand whether LUT is relevant to your business.
Week 3: Organise your records
- Create a digital invoice folder.
- Maintain a client and payment register.
- Organise bank and payment-platform statements.
- Set up a monthly accounting and reconciliation process.
Week 4: Build a compliance routine
- Prepare a GST compliance calendar if registered.
- Review applicable return deadlines.
- Monitor official notifications implementing the 57th Council recommendations.
- Consult a qualified GST professional for complex international transactions.
By following this process, you can spend less time worrying about tax confusion and more time developing your skills, serving clients and growing your business.
Conclusion: Financial Knowledge Is a Business Advantage
Freelancing offers opportunities to work independently, develop professional skills and serve clients across different countries.
But independence also comes with responsibilities.
You must understand your income, manage your expenses, maintain proper invoices, calculate your turnover and follow applicable tax requirements.
The 57th GST Council meeting has recommended reforms that could improve the experience of certain exporters and service providers. In particular, the proposed changes relating to export services and payment clarification deserve attention from freelancers working with international clients.
However, not every recommendation is an immediate legal change, and not every freelancer automatically qualifies for export benefits.
The best approach is to understand the existing rules, prepare your records and follow official notifications as the reforms are implemented.
Your skills help you earn. Your financial knowledge helps you manage what you earn. And your professional discipline helps you build a sustainable business.
At The Finance Mastery Hub, we believe that financial education should make business and money management easier to understand. No shortcuts, no unrealistic promises—just practical financial knowledge for a better future.
Disclaimer
This article is for educational and informational purposes only. GST treatment depends on the nature of the service, registration status, place of supply, client relationship, payment method and applicable law. The GST Council’s recommendations do not automatically become effective law. Verify the latest notifications and consult a qualified GST professional before taking a tax position.