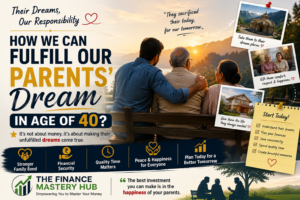

Turning 40 does not mean your biggest dreams are over. In fact, for many middle-class people, 40 can be the age when financial experience, career knowledge, and a clearer understanding of life come together. You may have family responsibilities, EMIs, children’s education, or limited savings—but you can still build a better financial future with the right strategy.
Start by Accepting Your Current Financial Reality
The first step is to stop comparing your financial life with other people. Social media can make it look like everyone is buying expensive cars, travelling internationally, or building wealth quickly. But you rarely see their loans, financial support, family wealth, or struggles.
Instead, calculate your actual financial position: monthly income, expenses, debt, savings, investments, insurance and net worth. Once you know where you stand, you can create a realistic plan.
Define What Your Dream Actually Costs
“Being financially successful” means different things to different people. Your dream might be buying a house, becoming debt-free, travelling with your family, starting a business, retiring early, or creating financial security for your children.
Write down your biggest three goals and attach an approximate financial value to each one. A dream becomes much easier to achieve when you turn it into a measurable financial target.
Don’t Try to Become Rich Quickly
One of the biggest mistakes people make after 40 is trying to recover lost time through risky investments or get-rich-quick opportunities.
Wealth creation generally requires patience, discipline and consistency. Avoid making major financial decisions simply because someone promises extraordinary returns.
Your priority should be to protect your existing income and savings while gradually building wealth.
Control High-Interest Debt
If you have credit-card debt, personal loans or other expensive debt, reducing it should become a major priority.
For example, if you receive a bonus or additional income, consider using part of it to reduce expensive debt instead of immediately increasing your lifestyle.
Becoming debt-free may not feel as exciting as buying something new, but it can create enormous financial freedom.
Build an Emergency Fund
At 40, financial responsibilities are often higher than they were in your 20s. A job change, medical emergency, family responsibility or unexpected expense can significantly affect your finances.
Building an emergency fund can help protect your long-term investments from being sold during difficult periods.
Keep the emergency money somewhere relatively safe and accessible rather than putting it into investments designed for long-term growth.
Increase Your Income, Not Just Your Savings
Cutting unnecessary expenses is important, but there is a limit to how much you can save from a fixed salary.
Increasing your earning capacity can have a much bigger long-term impact.
Learn skills that can increase your professional value. Depending on your career, these could include data analysis, technology, communication, financial analysis, management or specialised technical skills.
You can also explore legitimate side-income opportunities that fit your skills and available time.
Invest According to Your Goals
Investing should not be about finding the next investment that will double your money.
Instead, understand your goals, time horizon and ability to handle market fluctuations. Diversification and consistency are generally more useful than constantly trying to predict which investment will perform best.
For long-term goals, many people consider diversified equity investments, mutual funds and retirement-focused investments, but the right choice depends on individual circumstances.
Protect Your Family Before Chasing Wealth
Financial planning is not only about investments.
Adequate health insurance, appropriate life insurance where dependants rely on your income, emergency savings and proper financial documentation can protect the progress you have already made.
There is little value in building wealth if one unexpected event can completely destroy your family’s financial stability.
Use Your 40s to Build Your Second Financial Life
Your 40s can become a turning point.
You may already have decades of work experience. You understand your strengths and weaknesses better. You may also have a clearer idea of what you actually want from life.
Use this decade to increase your income, control debt, invest consistently, protect your family and avoid unnecessary financial risks.
You don’t need to become wealthy overnight.
You need to make better financial decisions consistently.
Your Dream Is Still Possible
Being from a middle-class family does not mean you have to give up on your dreams at 40.
Your path may be slower than someone who started with inherited wealth or a high income. That’s okay.
The goal isn’t to compete with someone else’s financial journey. The goal is to improve your own financial position year after year.
At 40, you may not have as much time as you had at 20—but you have something equally valuable: experience. Use that experience wisely, make a realistic plan, and give yourself the next 10 years to build the financial life you truly want.
Disclaimer – This article is for educational and informational purposes only and should not be considered personal tax or financial advice.